


12th Aug 2026. 8.56am

Regency View:
Update
Regency View:
Update
The latest reporting season has once again demonstrated that investors are rewarding businesses capable of executing well despite an uncertain economic backdrop. Across our portfolio, the strongest share price reactions came where management teams combined resilient trading with improved guidance, disciplined capital allocation or greater visibility over future earnings.
A recurring theme this fortnight has been confidence. Several companies strengthened their outlook for the remainder of the year, while others used their balance sheets to pursue acquisitions, return capital to shareholders or invest for future growth. Although macroeconomic uncertainty remains, operational execution continues to separate the winners from the rest of the market.
Admiral: Investing For The Next Phase Of Growth
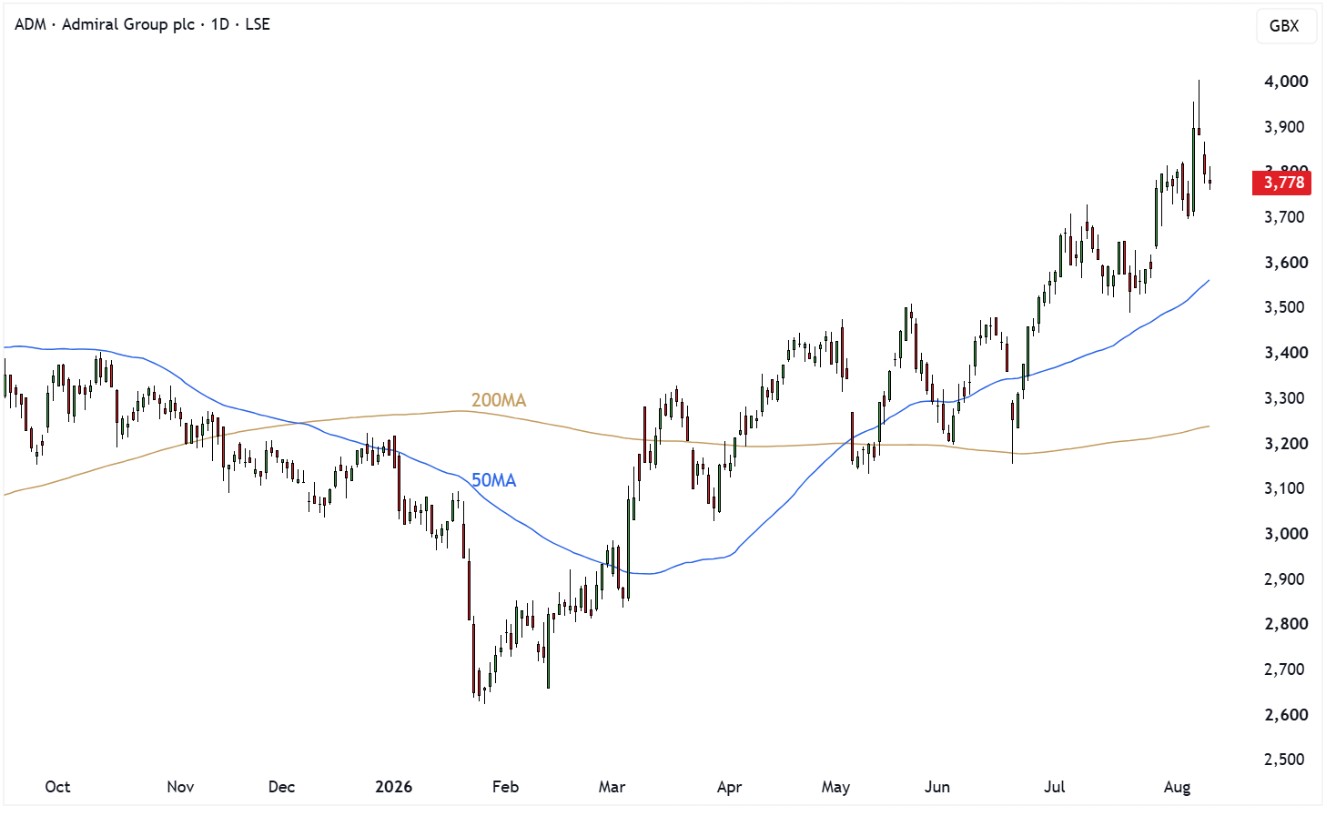
Admiral (ADM) shares moved higher after reporting another strong set of interim results that highlighted the resilience of its business despite a softer motor insurance pricing environment. While pre-tax profit fell 18% from a record first half in 2025 to £429 million, the result was broadly in line with the second half of last year and reflected management’s deliberate decision to prioritise long-term profitable growth over protecting short-term earnings. Customer numbers continued to expand, with total insurance risks increasing 5% to more than 12 million, while Admiral Money delivered another period of strong growth.
The market looked beyond the headline decline in profits and focused instead on the quality of the underlying business. The European insurance division returned to profitability, Admiral Money grew its loan book by 39%, and the recently acquired Flock business has already begun integrating into the wider group. Management also reiterated that claims inflation remains stable at 5-7%, while capital strength remained impressive with a post-distribution solvency ratio of 190%. Importantly, the group announced a new £45 million share buyback alongside its interim dividend, underlining continued confidence in cash generation.
Perhaps the most encouraging aspect of the update was management’s confidence in the long-term strategy. Admiral has already begun increasing UK motor pricing ahead of competitors as the insurance cycle softens, preferring to protect future profitability rather than chase market share. Combined with continued investment in technology, strong growth across non-motor insurance and expanding European operations, the business appears well positioned for the next phase of the insurance cycle.
What we are watching next: UK motor pricing trends, growth across European insurance and Admiral Money, and progress integrating Flock.
Themes: Interim Results | Insurance | Share Buyback | Customer Growth
ADM Daily Candle Chart
Atalaya Mining: Operations Continue To Deliver
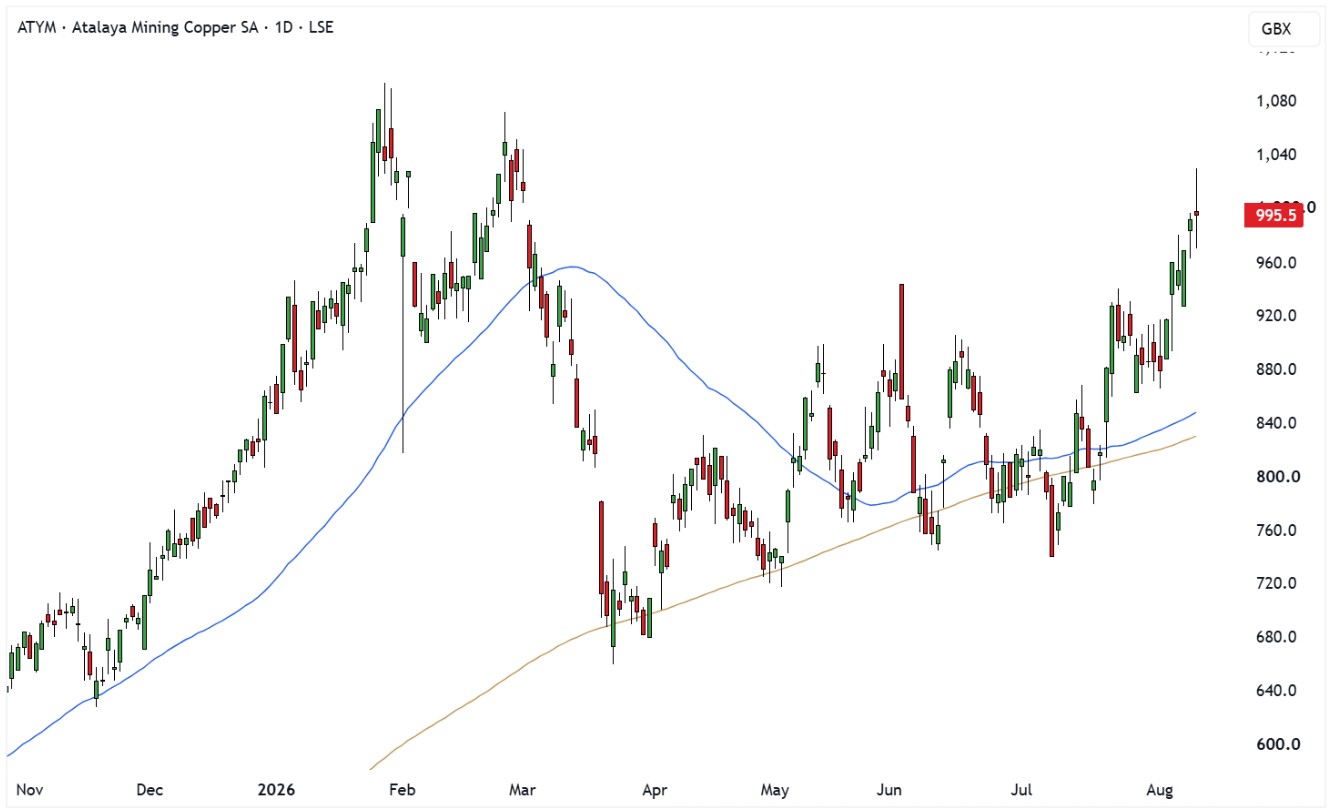
Atalaya Mining (ATYM) traded higher after delivering another solid operational update that reinforced confidence in the group’s production profile. Operational execution remains one of the company’s greatest strengths, with management continuing to demonstrate consistent delivery while progressing a number of longer-term growth initiatives across its asset base.
While commodity prices inevitably influence short-term earnings, investors increasingly appear focused on the company’s ability to expand production over time while maintaining operational discipline. Continued investment across its mining operations, together with a healthy balance sheet, leaves the group well positioned to benefit should copper markets remain supportive over the medium term.
The broader investment case remains closely linked to the long-term electrification theme. Demand for copper continues to be underpinned by renewable energy infrastructure, electric vehicles and grid expansion, and Atalaya remains one of the few London-listed companies offering direct exposure to these structural trends through an established producing asset.
What we are watching next: Production performance, project development milestones and movements in the copper price.
Themes: Mining | Copper | Operations | Production
ATYM Daily Candle Chart
Diageo: Restructuring Begins To Offset Trading Headwinds
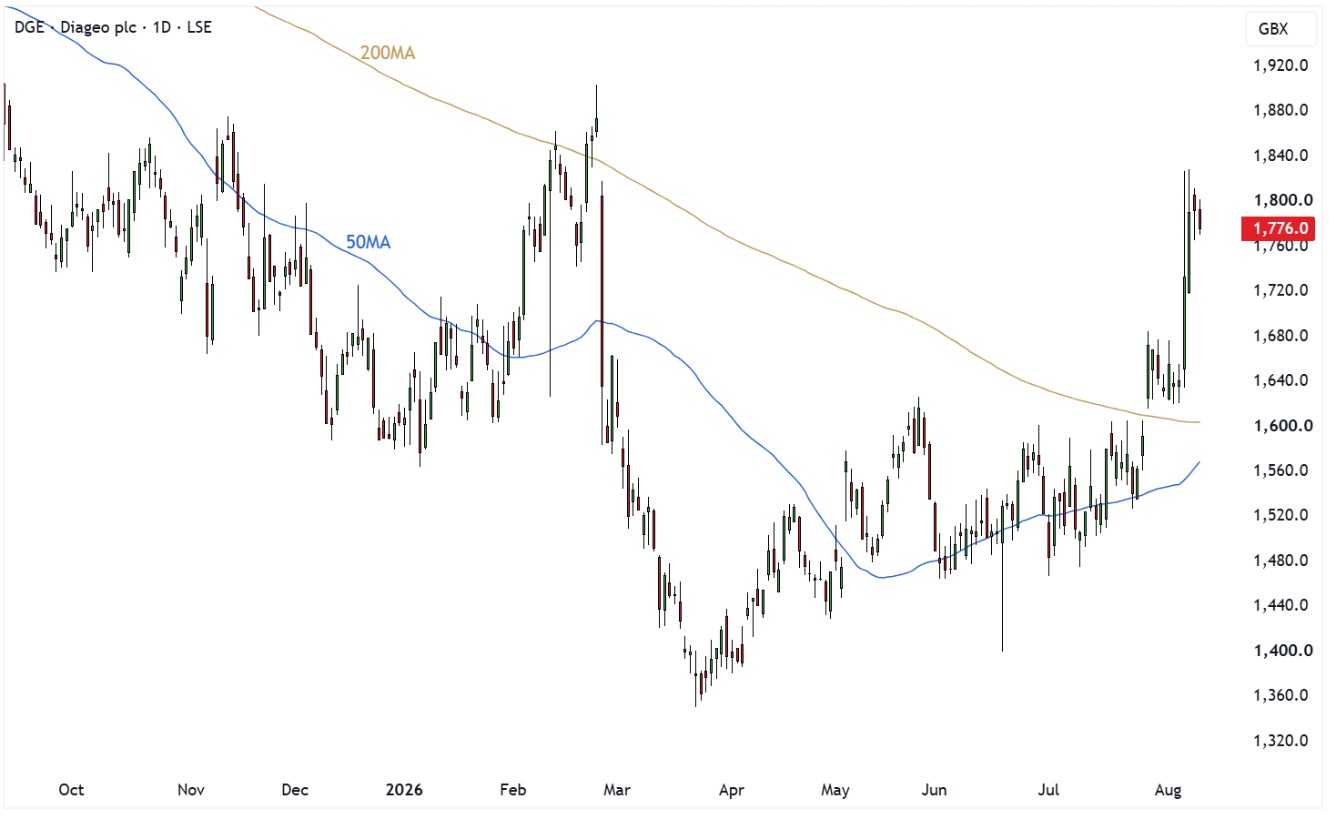
Diageo (DGE) shares moved higher despite reporting a 2% decline in organic sales, as investors focused on improving profitability, stronger cash generation and management’s restructuring plans rather than the headline revenue weakness. While North America and Asia Pacific remained challenging, stronger performances across Europe, Latin America and Africa helped offset some of the pressure.
Perhaps the most significant takeaway was the progress being made on the group’s two-year restructuring programme. Management expects the new operating framework to deliver around $850 million of annual savings over the next two years, creating additional flexibility to invest behind key brands without sacrificing profitability. Organic operating profit increased 2%, while operating margins also improved despite ongoing tariff pressures and adverse product mix.
Investors also welcomed continued improvements in cash generation, with free cash flow increasing by almost half a billion dollars during the year, allowing leverage to continue falling. Although the turnaround in North America remains an important priority, the market appears increasingly confident that Diageo is beginning to stabilise performance while laying the foundations for a more efficient and profitable business over the medium term.
What we are watching next: Progress of the restructuring programme, recovery in North American trading and delivery of planned cost savings.
Themes: Preliminary Results | Consumer Goods | Restructuring | Cash Generation
DGE Daily Candle Chart
Volution: Strengthening Its European Position
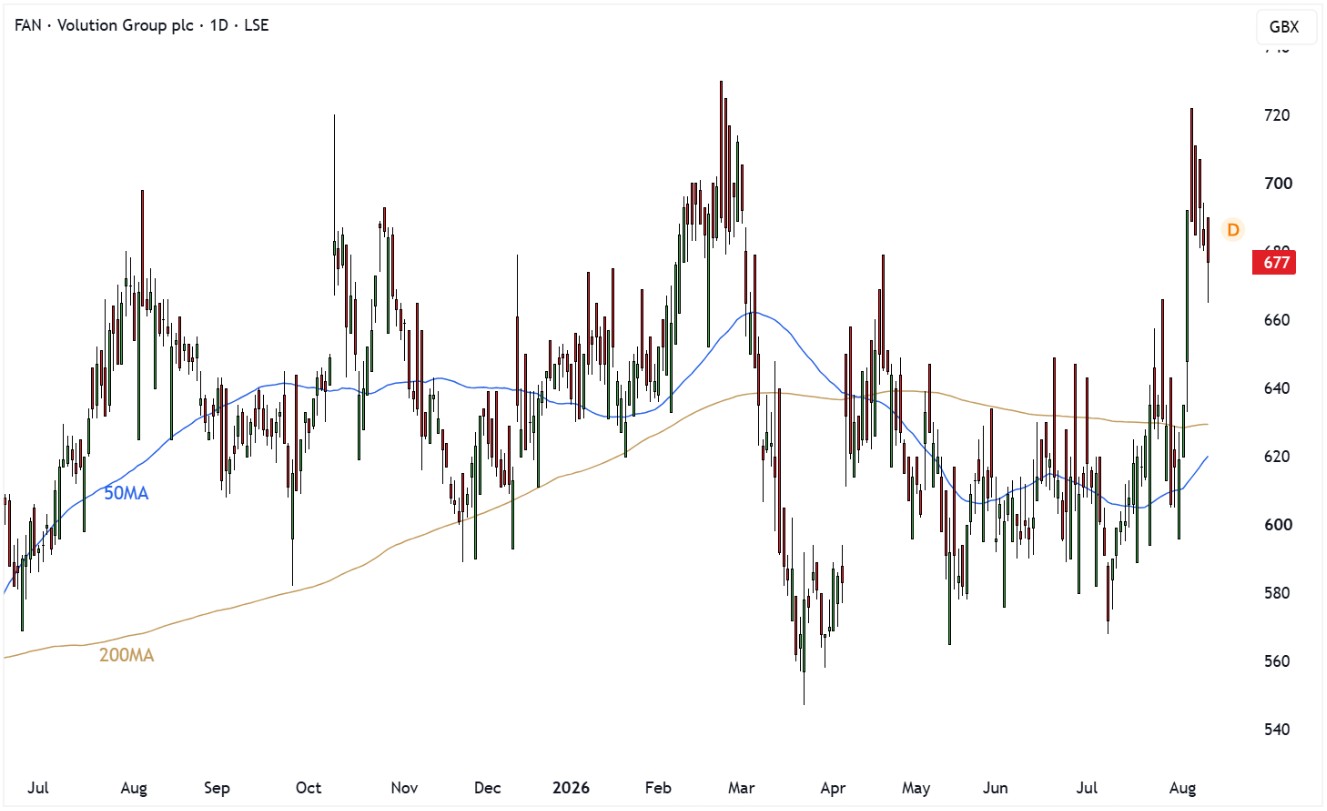
Volution (FAN) moved higher after announcing the acquisition of German ventilation specialist getAir for €40 million. The deal expands Volution’s presence within the fast-growing decentralised residential heat recovery ventilation market and further strengthens its position across continental Europe. Management expects the acquisition to be immediately earnings enhancing, continuing the company’s long track record of disciplined value-accretive acquisitions.
Strategically, the acquisition fits neatly into Volution’s existing portfolio. getAir is a market leader in decentralised heat recovery ventilation systems and complements Volution’s existing InVENTer business in Germany. The deal also strengthens the group’s research and development capabilities while broadening its exposure to one of Europe’s fastest-growing ventilation segments, driven by increasingly stringent building regulations and rising demand for energy-efficient homes.
The investment case continues to benefit from powerful structural tailwinds. Governments across Europe remain focused on improving building energy efficiency while consumers seek lower energy costs, creating long-term demand for heat recovery ventilation systems. Combined with Volution’s proven acquisition strategy and strong balance sheet, the latest transaction further reinforces confidence in the group’s long-term growth prospects.
What we are watching next: Integration of getAir, continued acquisition opportunities and growth in residential heat recovery ventilation demand.
Themes: Acquisition | Building Products | Energy Efficiency | Continental Europe
FAN Daily Candle Chart
4imprint: Quality Continues To Shine
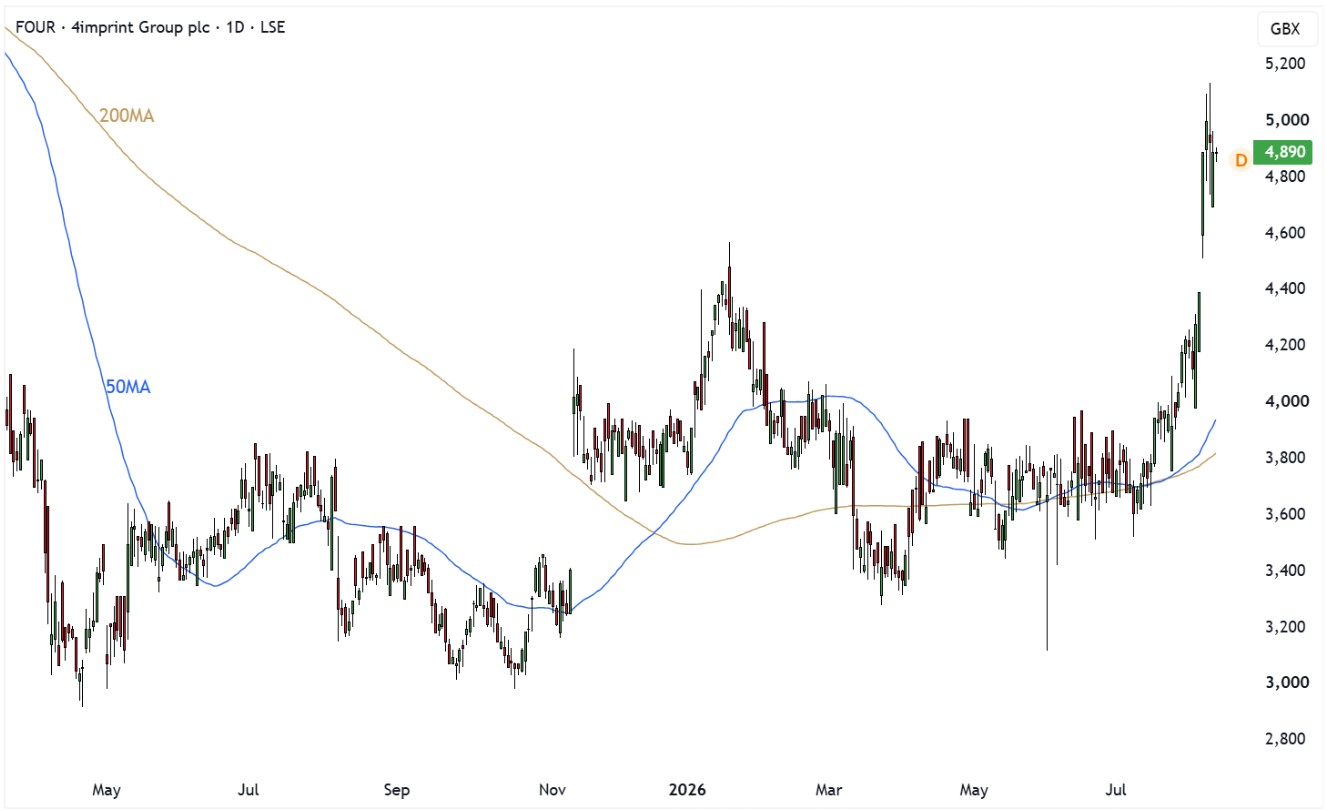
4imprint (FOUR) once again demonstrated the resilience of its business model despite a more challenging trading backdrop. Although revenue growth has moderated compared with recent years, the company continues to generate exceptional levels of cash while maintaining industry-leading profitability. Investors responded positively to another reassuring update, recognising the strength of both the balance sheet and the group’s long-term competitive position.
One of 4imprint’s defining characteristics remains its disciplined approach to capital allocation. Rather than chasing growth at the expense of margins, management continues to focus on profitable customer acquisition while maintaining exceptionally high levels of cash generation. This financial strength provides considerable flexibility to continue investing through the economic cycle while supporting attractive shareholder returns.
Although promotional products remain closely linked to broader business confidence, 4imprint has consistently demonstrated its ability to outperform competitors over the long term. Its combination of market leadership, operational discipline and cash generation continues to justify the premium valuation the shares have commanded for many years.
What we are watching next: Customer demand trends, marketing investment and continued cash generation.
Themes: Interim Results | Promotional Products | Cash Generation | Capital Allocation
FOUR Daily Candle Chart
IG Group: A Strategic Bet On Future Growth
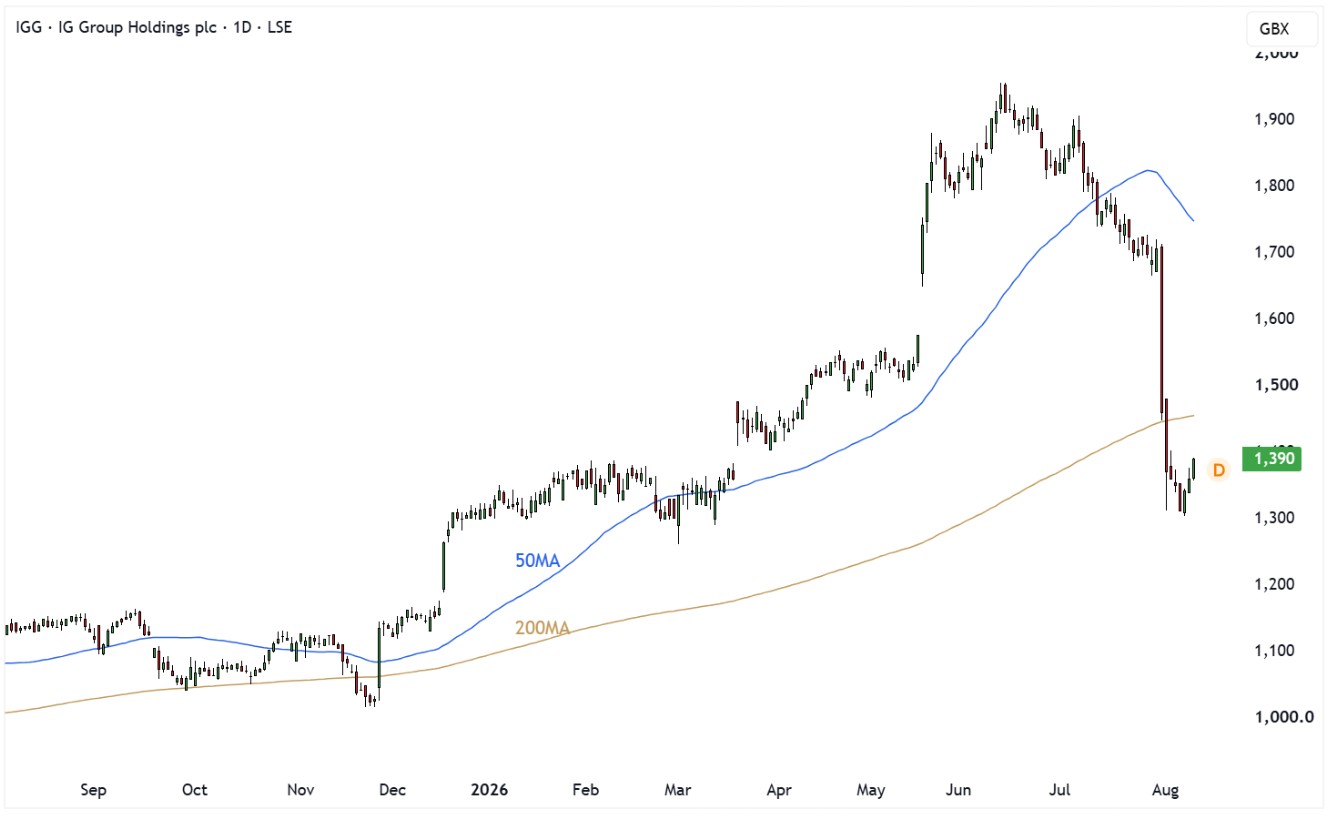
IG Group (IGG) shares fell sharply after announcing the $1.3 billion acquisition of US-based fantasy sports and prediction markets operator Underdog. While strategically significant, investors appeared concerned by both the scale of the transaction and management’s decision to pause the ongoing share buyback programme to help fund the acquisition.
The deal represents one of the largest acquisitions in IG’s history and reflects management’s ambition to diversify beyond its traditional leveraged trading business. Prediction markets and sports-based financial products are growing rapidly in the United States, and the acquisition provides immediate exposure to an attractive, high-growth market. However, large acquisitions inevitably introduce execution risk, particularly where integration, regulation and future profitability remain uncertain.

The negative share price reaction reflects this uncertainty rather than any deterioration in the underlying business. Investors will ultimately judge the transaction on management’s ability to successfully integrate Underdog, accelerate earnings growth and demonstrate that the acquisition creates long-term shareholder value. In the meantime, the suspension of the buyback programme removed an important source of support for the shares, explaining much of the immediate market reaction.
What we are watching next: Regulatory developments, integration progress and management’s long-term capital allocation plans.
Themes: Acquisition | Online Trading | United States | Capital Allocation
IGG Daily Candle Chart
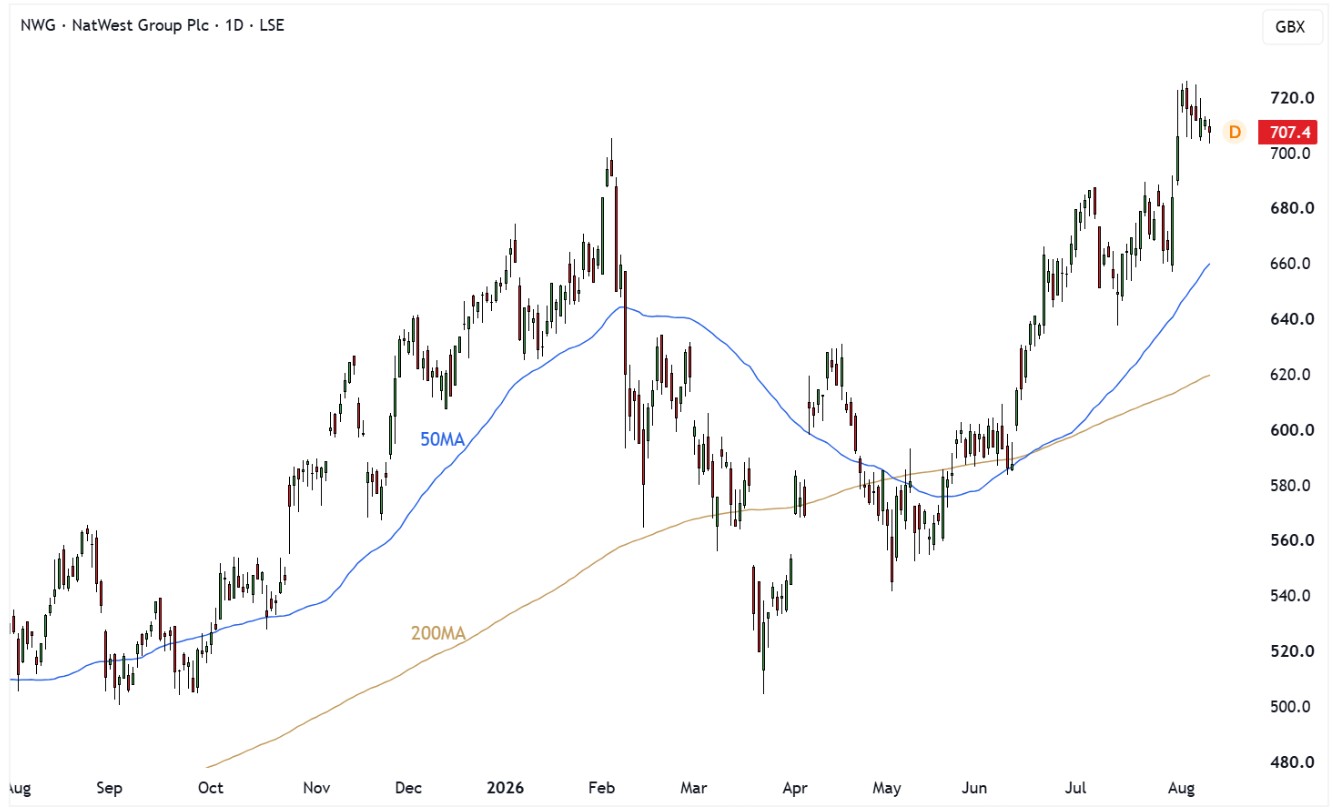
NatWest Group: Returning More Capital To Shareholders
NatWest (NWG) continued its impressive run after reporting another strong set of interim results, with investors particularly encouraged by improving profitability, robust capital generation and another significant increase in shareholder returns. The bank continues to benefit from resilient lending activity, disciplined cost control and healthy deposit balances, allowing management to further strengthen its capital return strategy.
Alongside solid underlying financial performance, management announced an expanded capital return programme, reinforcing confidence in the strength of the balance sheet. Capital ratios remain comfortably above regulatory requirements, providing flexibility to continue investing in the business while maintaining generous shareholder distributions. Despite expectations that interest rates will gradually decline, NatWest continues to demonstrate that it can deliver attractive returns through disciplined execution rather than relying solely on higher net interest margins.
The investment case has evolved considerably over recent years. What was once viewed as a restructuring story has become a highly cash-generative retail and commercial bank capable of delivering consistent earnings and attractive capital returns. As the UK government’s shareholding continues to reduce, investor attention is increasingly shifting towards the sustainability of earnings and the group’s ability to continue growing returns over the medium term.
What we are watching next: Loan growth, net interest margins, capital generation and further shareholder distributions.
Themes: Interim Results | Banking | Capital Returns | Share Buybacks
NWG Daily Candle Chart
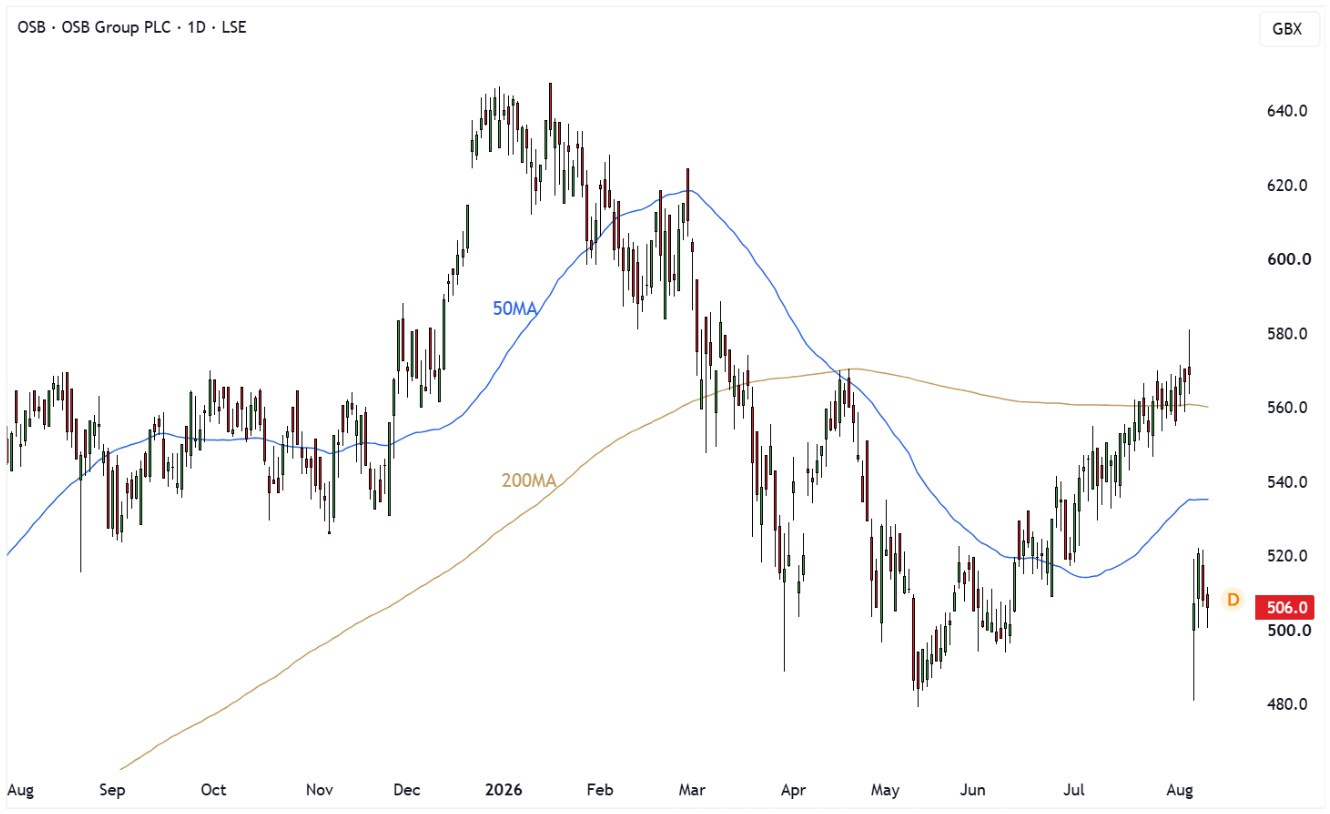
OSB Group: Margin Pressure Weighs On Sentiment
OSB Group (OSB) came under pressure following its latest results as investors focused on softer profitability and continued pressure on lending margins. Although the specialist lender remains highly profitable and well capitalised, management acknowledged that competition across the mortgage market continues to weigh on returns, particularly within the buy-to-let sector.
While the headline numbers disappointed relative to market expectations, there were also several positives within the update. Asset quality remains robust, arrears continue to be well controlled and the balance sheet remains strong. Management also reiterated its disciplined underwriting standards, preferring to protect long-term profitability rather than chase market share in an increasingly competitive lending environment.
The share price weakness reflects concerns over the earnings outlook rather than the financial strength of the business itself. Investors will want to see evidence that mortgage pricing begins to improve as competitive pressures ease and funding costs continue to normalise. In the meantime, OSB’s attractive valuation, strong capital position and resilient loan book continue to provide support for the longer-term investment case.
What we are watching next: Net interest margin trends, mortgage pricing, lending growth and credit quality.
Themes: Interim Results | Specialist Banking | Mortgages | Net Interest Margin
OSB Daily Candle Chart
Disclaimer:
All content is provided for general information only and should not be construed as any form of advice or personal recommendation. The provision of this content is not regulated by the Financial Conduct Authority.