


3rd Sep 2026. 9.08am

Regency View:
Update
Regency View:
Update
It has been a busy fortnight across the AIM Investor portfolio, with a mixture of strong financial results, new contract wins and a couple of developments requiring closer attention. Central Asia Metals has been the standout performer operationally, while Nexteq’s latest design win provides an encouraging sign of progress within Densitron. Elsewhere, eEnergy has encountered a short-term working capital squeeze, PetroTal is preparing for the resumption of drilling at Bretana, and TPXimpact continues to build visibility through new contract awards.
Central Asia Metals: Cash generation moves sharply higher
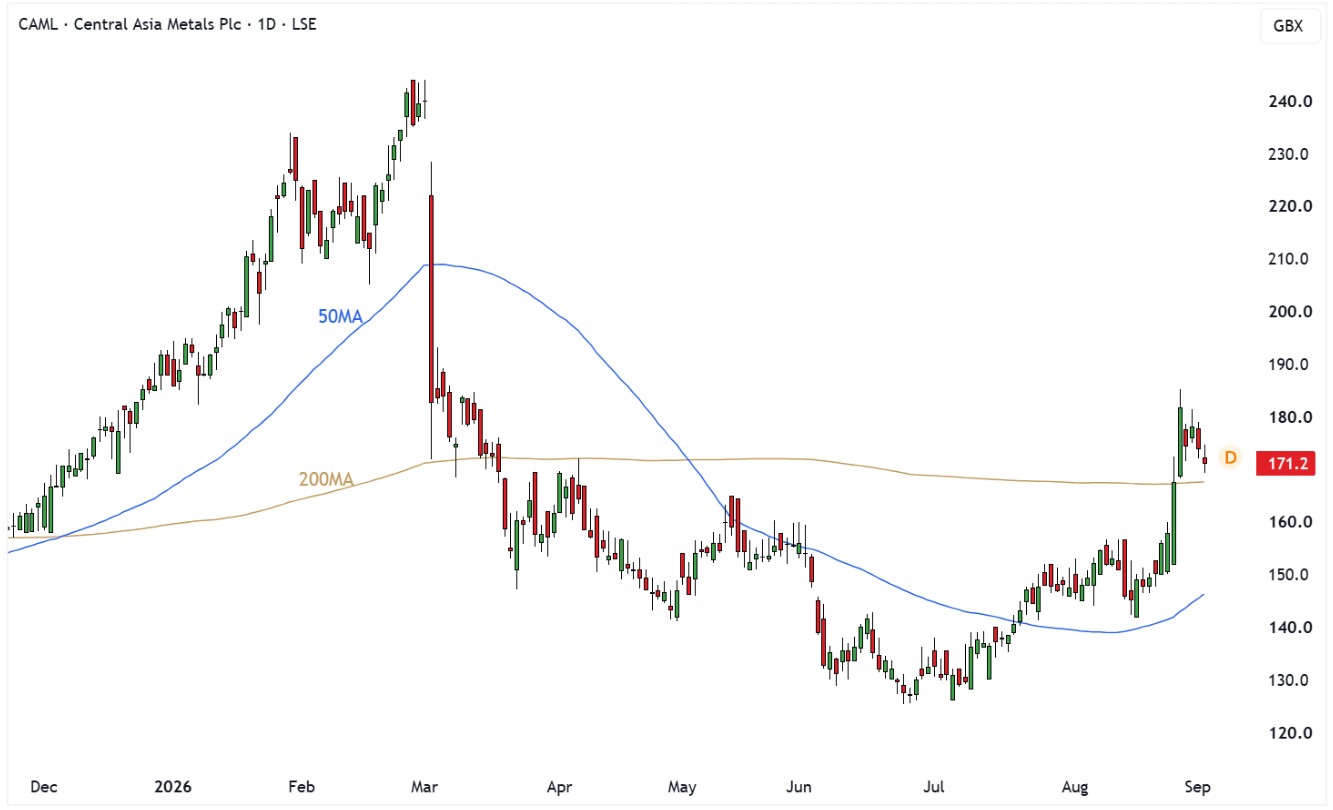
Central Asia Metals (CAML) has delivered a strong set of first-half results, helped by the combination of higher commodity prices and increased production across all three of its metals. Revenue rose 46% to $145.5m, while EBITDA increased 89% to $75.5m, lifting the EBITDA margin from 40% to 52%. Profit before tax more than trebled to $59.3m. Copper production at Kounrad edged 1% higher, while Sasa delivered 5% growth in zinc production and 6% growth in lead, providing encouraging evidence that recent operational improvements are having an effect.
The most impressive feature of the results is the amount of cash being generated. Adjusted free cash flow increased 189% to $46.8m, while CAML finished June with net cash of $96.3m despite completing a $10m share buyback during the period. That has allowed the Board to increase the interim dividend from 4.5p to 8p per share, equivalent to 40% of adjusted free cash flow. Commodity prices have clearly provided a substantial tailwind, with the average copper price received increasing 39%, but the ability to convert that backdrop into cash while simultaneously strengthening the balance sheet is important.
The next stage of the story could look rather different following the proposed acquisition of Cygnus Metals. The all-share deal would add the Chibougamau copper-gold project in Québec, increasing CAML’s exposure to copper and introducing a potentially significant new growth asset alongside its established cash-generative operations. Acquisitions of development-stage assets inevitably introduce execution risk, but CAML is approaching the transaction with a strong balance sheet and its existing operations performing well. Full-year production guidance has also been maintained, leaving the underlying business in good shape as management looks to broaden the group’s longer-term growth profile.
What we are watching next: Shareholder approval and completion of the Cygnus transaction, alongside upcoming exploration results from Kazakhstan and continued progress at Sasa during the second half.
Themes: Interim Results | Cash Generation | Dividend Growth | Copper | Cygnus Acquisition
CAML Daily Candle Chart
eEnergy: Delayed payments tighten working capital
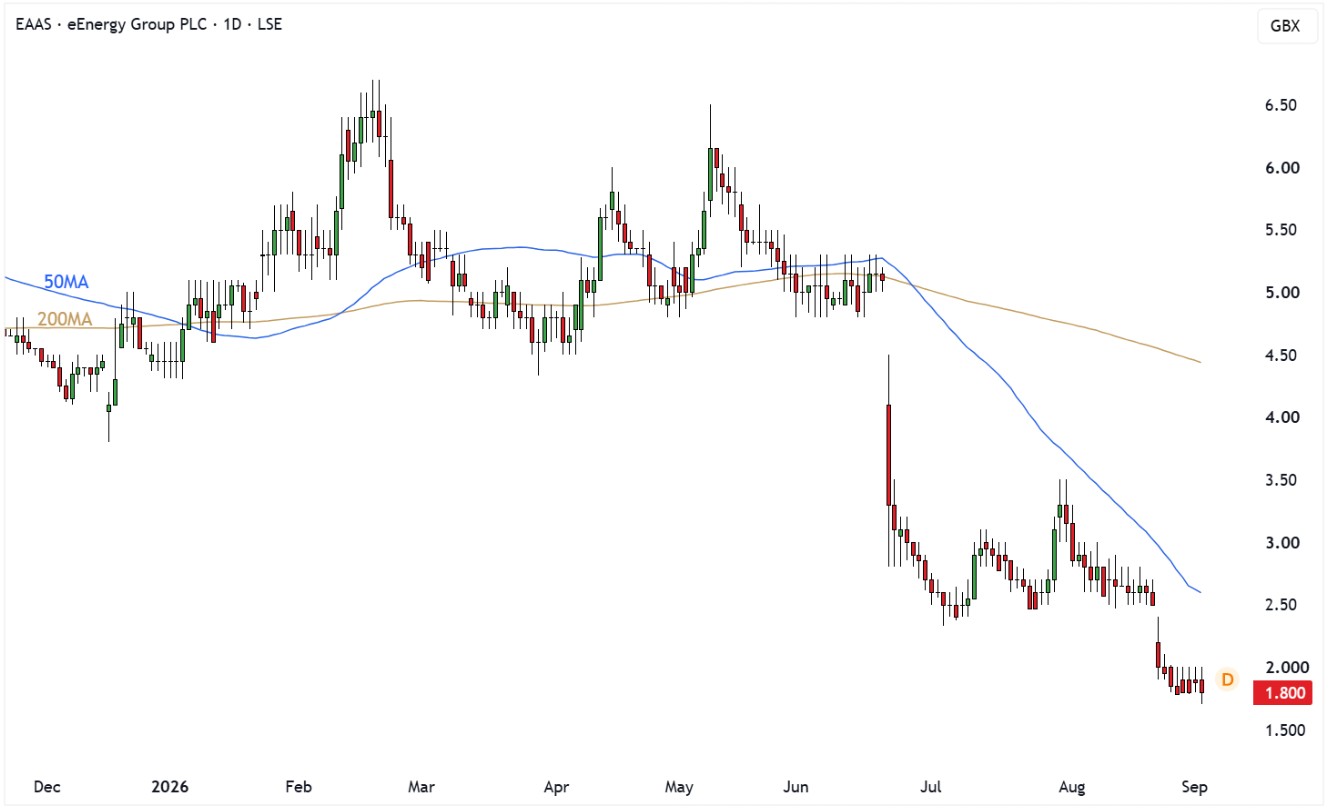
eEnergy (EAAS) shares have come under pressure after the company revealed delays in receiving approximately £3.2m relating to work completed on the Mace project. All 65 sites are now fully operational and energised with the group’s solar PV, LED lighting, battery storage and EV charging products, but completion paperwork, principally relating to the solar installations, has held up payment. Management expects the process to be finalised over the coming months.
The delay has created a short-term working capital requirement. eEnergy has extended the repayment date on the remaining £0.5m of its Harwood loan from November 2026 to February 2027 and has secured an additional £0.5m loan from former director and existing shareholder Nigel Burton. Both facilities carry interest of 1% per month, with the new loan also attracting a 1% arrangement fee. The additional liquidity provides some breathing room, but the relatively high cost of the borrowing underlines the importance of collecting the outstanding Mace payments promptly.
There is an important distinction between delayed payment for work that has already been completed and a problem with the underlying customer or project, and the announcement points towards the former. Nevertheless, £3.2m is a meaningful receivable for eEnergy and the need to arrange additional short-term funding highlights how sensitive the business remains to movements in working capital. The market’s cautious reaction is therefore understandable. Confirmation that the paperwork has been completed and the outstanding cash received would go a long way towards removing this concern, but until then we need to keep a closer eye on liquidity.
What we are watching next: Receipt of the outstanding £3.2m from the Mace project and whether this allows eEnergy to move beyond its current reliance on short-term borrowing.
Themes: Working Capital | Mace Project | Payment Delays | Loan Facility | Cash Flow
EAAS Daily Candle Chart
Nexteq: Densitron opens the door to automotive
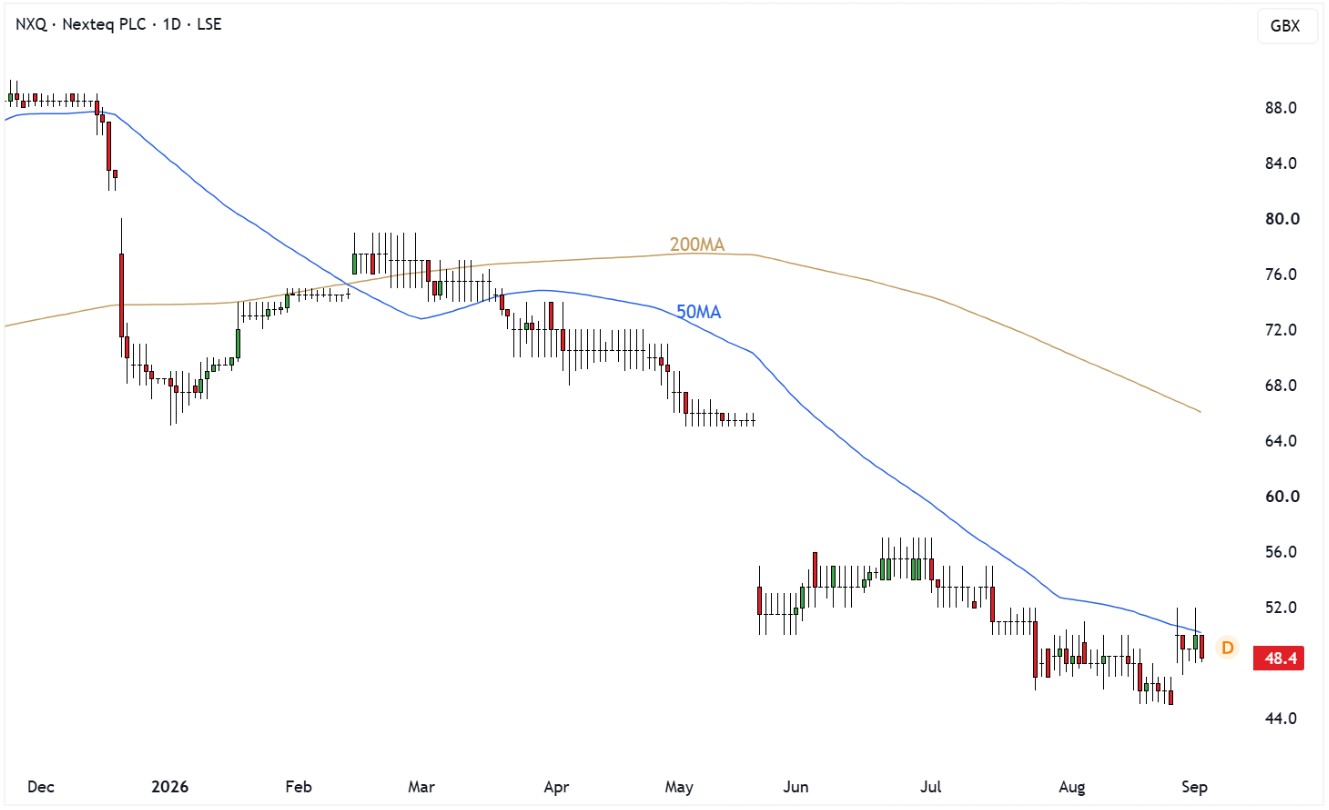
Nexteq (NXQ) has secured a strategically interesting new customer through its Densitron display technology business. A leading supplier of automotive electronics has selected Densitron to provide customised display solutions for a new electric delivery vehicle application. Production is expected to begin during the second half of FY26, with volumes then anticipated to increase materially over the following three years as the customer’s product rollout expands.
No contract value has been disclosed, so the significance of the announcement lies more in the potential development of the relationship than its immediate contribution to revenue. Densitron has provided customised engineering and specification work to meet the customer’s requirements, which fits Nexteq’s strategy of moving towards higher-value, differentiated technology solutions rather than competing primarily on standard products. It also takes the group into the automotive and transportation sector, further diversifying its exposure beyond its established industrial markets.
The expected ramp-up in production volumes is what makes this design win particularly interesting. Customised components that become embedded within a customer’s finished product can create relatively long production runs, although much will ultimately depend on the success and scale of the customer’s own rollout. We therefore shouldn’t attach too much financial significance to the contract before those volumes arrive, but it provides another useful sign that Densitron’s engineering-led strategy is converting into new customers and new applications.
What we are watching next: The start of production during H2 FY26 and evidence over the following periods that the expected increase in volumes is beginning to make a meaningful contribution to Densitron.
Themes: Contract Win | Densitron | Automotive | Electric Vehicles | Revenue Diversification
NXQ Daily Candle Chart
PetroTal: Preparing to restart the drill bit
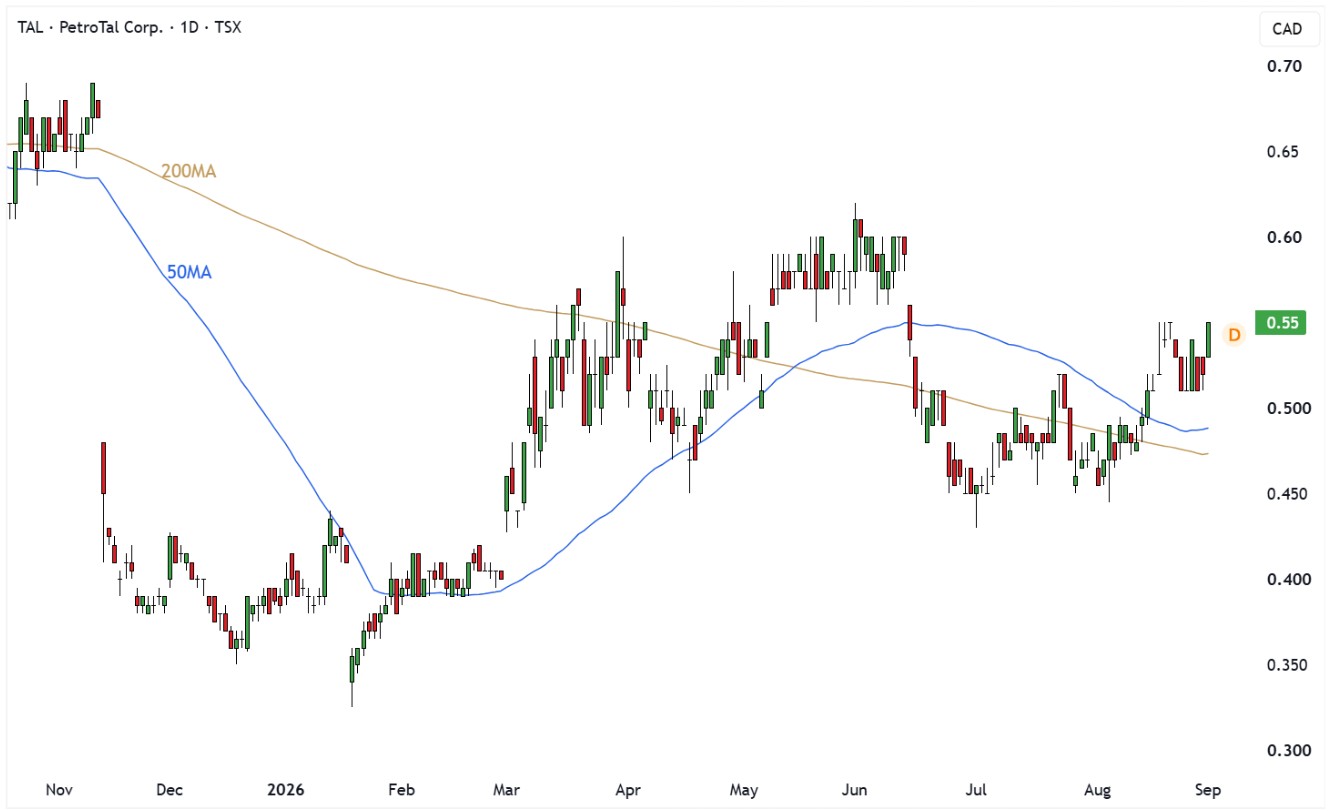
PetroTal (PTAL) averaged production of 12,557 barrels of oil per day during the second quarter, taking first-half production to 13,726 bopd and leaving the company around 3% ahead of budget. Second-quarter sales averaged 11,969 bopd, while adjusted EBITDA reached $43.5m. PetroTal also finished June with total cash of $136.8m, including $105.3m of unrestricted cash, supported by operating cash generation and the $13.4m sale of its Amazonia-1 drilling rig.
The main issue remains the natural decline in production from existing wells at the Bretana field. Management has been expecting this and has begun replacing pumps and tubing across four to five wells in an effort to improve production deliverability during the second half. Full-year production guidance remains unchanged at 12,000 bopd, meaning the expected downtime and declining output from mature wells are already reflected in the company’s plans. The $10.2m impairment associated principally with the drilling rig disposal also weighed on reported net income, but does not change the underlying cash position.
The more important development for the investment case comes in October, when PetroTal expects to restart development drilling at Bretana. Management sees this as the catalyst for returning the business to production growth during 2027, making the current period more of a transition between drilling campaigns. PetroTal’s substantial cash balance gives it considerable flexibility heading into that programme, so our attention is increasingly shifting away from the expected near-term production decline and towards whether the next group of wells can establish a fresh upward trajectory next year.
What we are watching next: The resumption of development drilling at Bretana in October, progress from the ongoing pump and tubing replacement programme and the first indications of how production could develop into 2027.
Themes: Q2 Results | Bretana | Production | Development Drilling | Cash Position
PTAL Daily Candle Chart
TPXimpact: Contract momentum builds
TPXimpact (TPX) has continued to add to its contracted workload, with a series of public-sector awards strengthening visibility over future revenues. The latest developments include additional work with HM Land Registry alongside a new contract secured through the group’s Manifesto digital experience business. This follows other sizeable awards secured during the year and provides further evidence of TPXimpact’s strong position within public-sector digital transformation.
There are two encouraging elements to the recent contract momentum. The first is the ability to secure additional work from existing customers, which suggests clients are satisfied with delivery and provides an opportunity to deepen established relationships. The second is the continued addition of new projects across the group, broadening the contracted revenue base. That combination is particularly useful for TPXimpact because the investment case has gradually moved beyond restructuring and towards demonstrating that the simplified business can generate sustainable organic growth.
The growing order book therefore gives management a stronger platform, but winning work is only part of the equation. The next step is converting that workload into profitable revenue and, importantly, cash. TPXimpact has made considerable progress improving the underlying business over recent years, and greater forward revenue visibility should make it easier to demonstrate the benefits of that work. Continued contract momentum is encouraging, but further improvement in margins and cash generation will ultimately determine how much value is created from it.
What we are watching next: Conversion of the growing contracted backlog into revenue, continued margin development and evidence that stronger trading is feeding through into cash generation.
Themes: Contract Wins | Public Sector | Digital Transformation | Revenue Visibility | Cash Generation
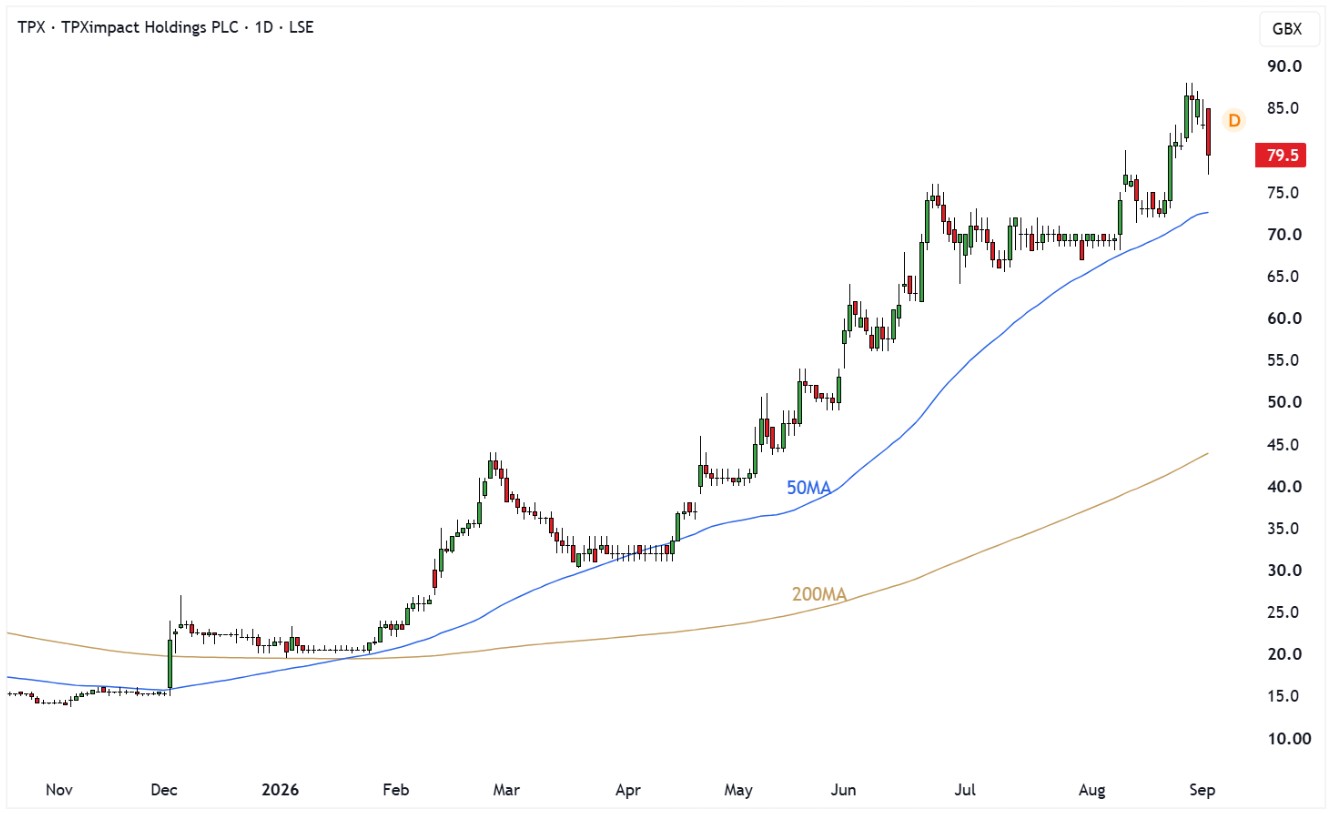
TPX Daily Candle Chart
Disclaimer:
All content is provided for general information only and should not be construed as any form of advice or personal recommendation. The provision of this content is not regulated by the Financial Conduct Authority.