


20th Aug 2026. 9.02am

Regency View:
Update
Regency View:
Update
As another earnings season draws towards its conclusion, the pace of company announcements has naturally begun to slow. That said, quieter newsflow does not necessarily mean fewer opportunities. Some of the most significant share price moves over the past fortnight have come from companies either upgrading expectations, warning on trading, or becoming the subject of takeover activity.
This fortnight’s update highlights a good reminder of how quickly sentiment can shift. Strong operational execution continues to be rewarded, as demonstrated by CML Microsystems, while GB Group illustrated how even modest changes to growth expectations can trigger a sharp market reaction. Elsewhere, Synectics continues laying the foundations for longer-term expansion, while Time Finance’s successful turnaround has culminated in a recommended takeover offer at a substantial premium.
CML Microsystems: Recovery Gathering Momentum
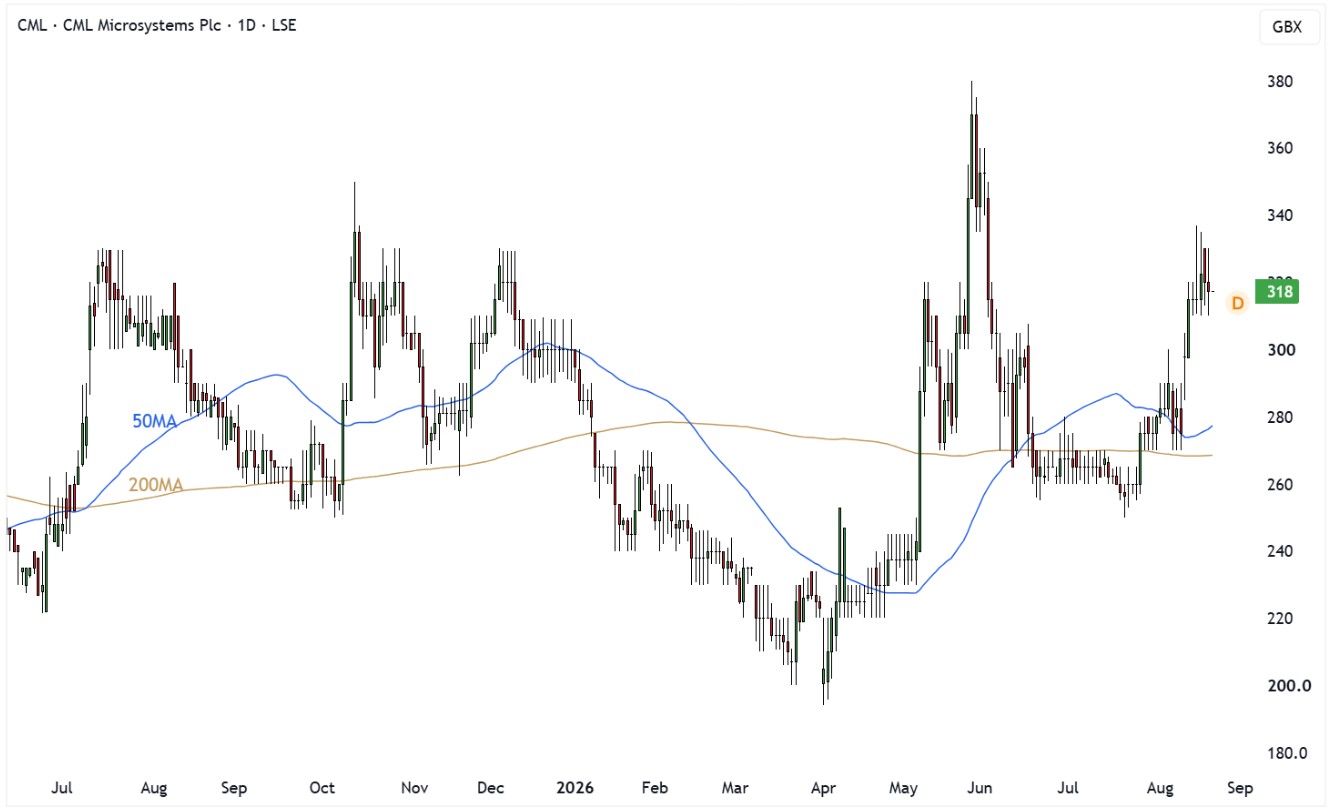
CML Microsystems moved higher after delivering an encouraging trading update at its Annual General Meeting, with management highlighting improving demand across all of its core communications markets. Following a difficult period for the semiconductor sector, the business has entered the new financial year with noticeably stronger momentum, supported by both improving revenues and a healthier order intake.
Perhaps the most significant development was management’s increased confidence around profitability. Having already finished the previous financial year with an improving final quarter, trading has continued to strengthen during the opening months of FY27, with revenues meeting expectations and order intake running ahead of plan. As a result, the Board now expects the group to return to operational profitability earlier than previously anticipated, suggesting the recovery is gathering pace more quickly than expected.
While semiconductor demand can remain cyclical, the latest update provides further evidence that inventory normalisation across the industry may now be largely behind the company. Combined with CML’s exposure to specialist communications markets rather than mainstream consumer electronics, investors appear increasingly confident that earnings have reached an important turning point.
What we are watching next: Progress towards operational profitability, order intake across communications markets and confirmation that the recovery continues through the second half.
Themes: AGM Update | Semiconductors | Communications | Return To Profitability
CML Daily Candle Chart
GB Group: Growth Expectations Reset
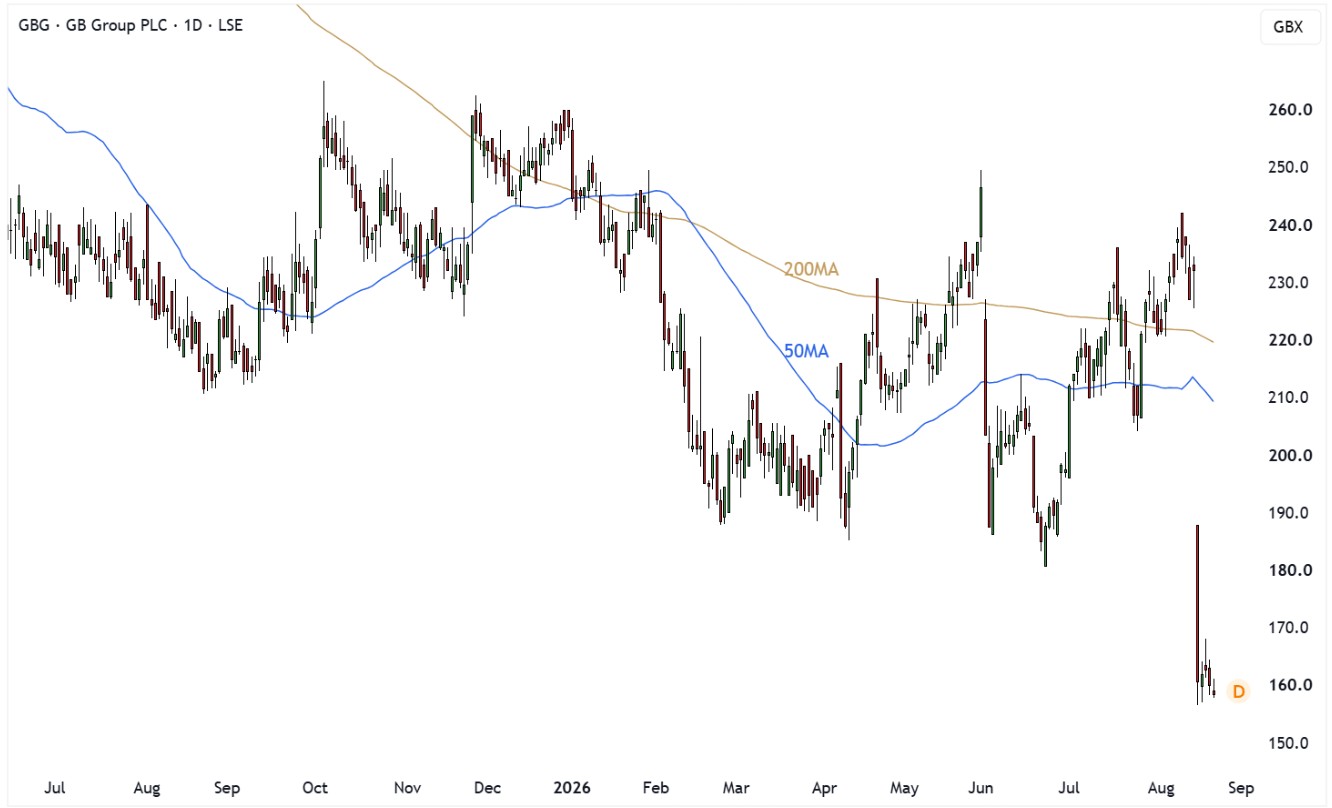
GB Group suffered one of the largest declines across the AIM market after warning that growth within its Americas Identity division has failed to recover as expected. While first-quarter trading had been broadly in line with management expectations, higher-than-anticipated customer attrition during the second quarter has led the company to reduce full-year revenue growth guidance from mid-single digits to between 1% and 3%.
Importantly, the issue appears to be largely regional rather than structural. Trading across EMEA continues to perform well, supported by ongoing momentum behind GBG Go, the company’s AI-powered identity verification platform. However, the longer sales cycles typically associated with enterprise software mean new customer wins are unlikely to offset lost revenues quickly enough to materially benefit the current financial year. Management also confirmed it will continue investing £6 million into accelerating the development of GBG Go despite the weaker revenue outlook, while maintaining strict cost control to protect margins.
The sharp share price reaction reflects the market’s sensitivity to slowing growth rather than any deterioration in the underlying technology. Identity verification remains an attractive structural market, and GB Group retains a strong competitive position globally. Nevertheless, investors will now be looking for evidence that customer attrition stabilises in North America and that management can successfully convert its healthy sales pipeline into renewed growth over the coming quarters.
What we are watching next: Stabilisation within the Americas business, customer retention and commercial adoption of GBG Go.
Themes: Trading Update | Identity Verification | Software | Guidance Downgrade
GBG Daily Candle Chart
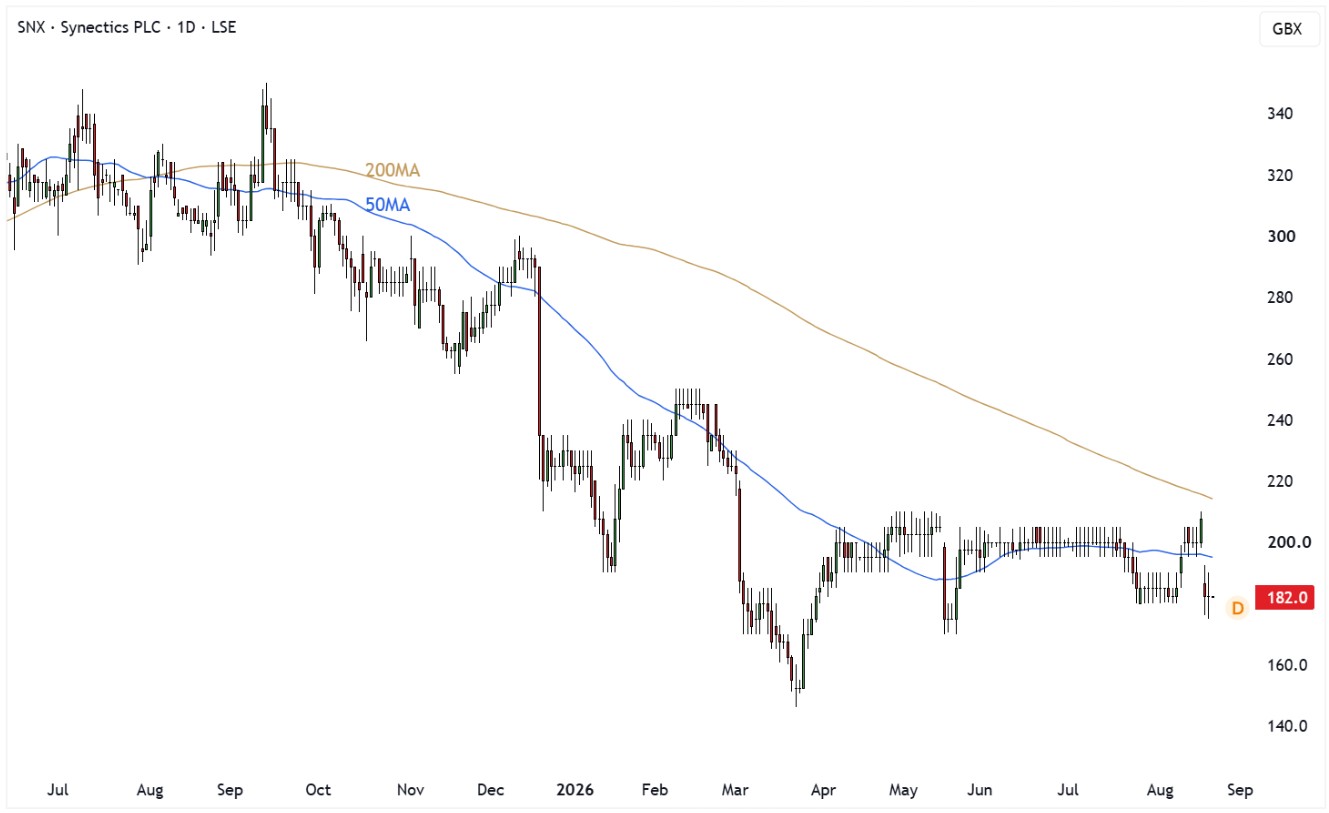
Synectics: Building For The Next Phase Of Growth
Synectics delivered interim results that were largely in line with expectations, although the shares came under pressure as investors focused on lower year-on-year earnings and continued uncertainty surrounding the timing of energy sector projects. Revenue fell to £22.2 million following the absence of a large one-off gaming contract that boosted last year’s first half, while delays to several Middle East energy projects also weighed on performance. Even so, management maintained confidence that full-year expectations remain achievable, albeit with the outcome dependent on the timing of contract awards during the second half.
While the headline numbers appeared weaker, the underlying strategic progress remains encouraging. Gross margins improved significantly to 48%, reflecting a greater emphasis on higher-value software and product revenues, while the company continued executing its recently announced ‘5P’ transformation strategy. During the period Synectics launched new AI-enabled software products, achieved UK Government CAPSS cyber security certification and secured several notable contract wins across transport, energy and critical infrastructure markets. Management believes these investments will create a more scalable, product-led business capable of delivering stronger recurring revenues from FY27 onwards.

The investment case increasingly centres on what the business could become rather than where it stands today. Management is investing ahead of future growth, building commercial capability, strengthening partner relationships and expanding its AI-enabled software offering. Although some uncertainty remains over the timing of energy projects, the Board continues to highlight a healthy pipeline of opportunities and believes the foundations are now largely in place for accelerated growth beyond the current financial year.
What we are watching next: Conversion of the energy project pipeline, adoption of new AI-enabled software products and evidence that the transformation strategy begins driving stronger financial performance.
Themes: Interim Results | Security Technology | Artificial Intelligence | Digital Transformation
SNX Daily Candle Chart
Time Finance: A Successful Turnaround Ends In A Takeover
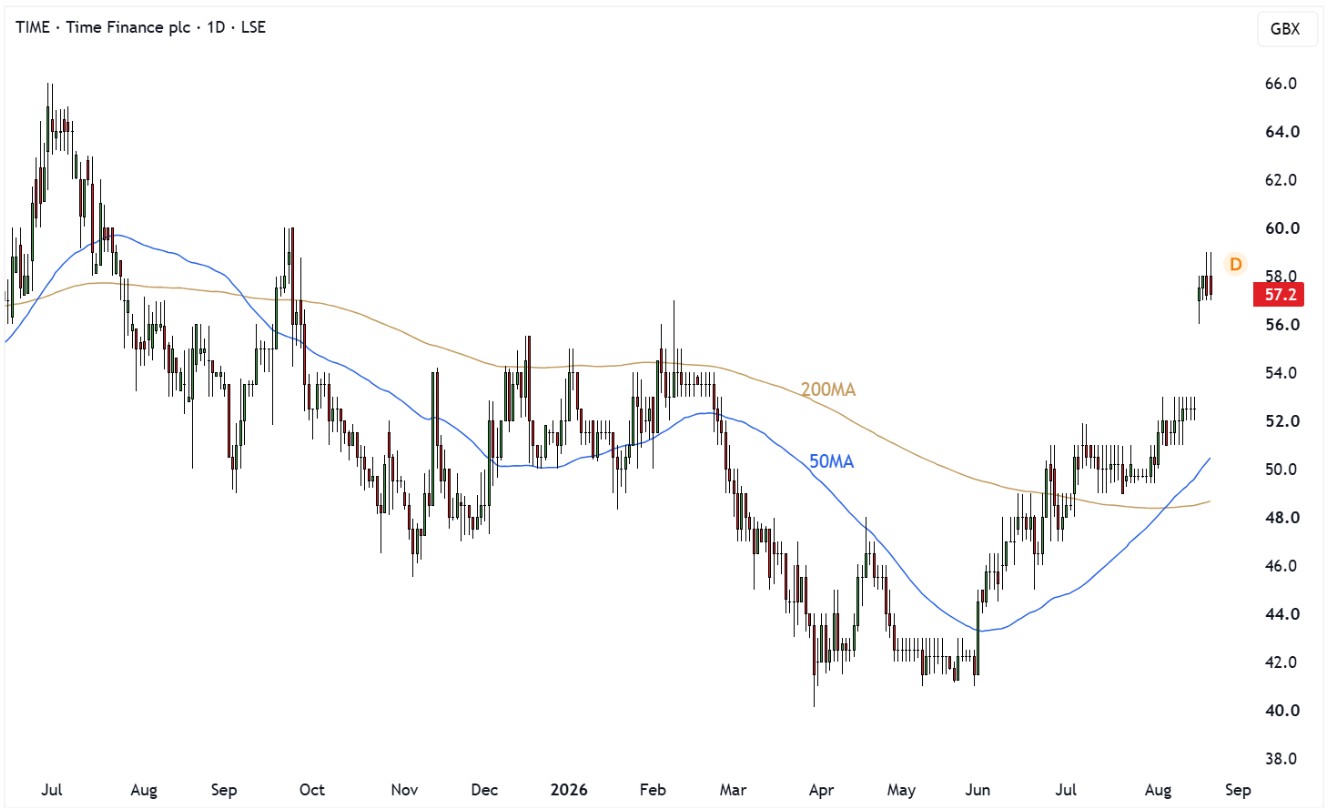
Time Finance surged after agreeing to a recommended cash acquisition by Bentley Park, the parent company of Ultimate Finance, at 59.1p per share. The offer values the business at approximately £55 million and represents a premium of around 23.5% to the three-month average share price, bringing an end to one of AIM’s more successful turnaround stories in recent years.
The proposed acquisition is a clear reflection of the progress Time Finance has made as an independent business. Management has consistently grown its lending book over the past five years, delivering twenty consecutive quarters of loan book growth while building a profitable, well-capitalised specialist lender focused on UK SMEs. Bentley Park believes combining Time Finance with Ultimate Finance will create a significantly larger alternative lending platform, with a combined loan book approaching £650 million and meaningful opportunities to cross-sell products, broaden distribution and improve operational scale.

For existing shareholders, the offer crystallises the value created through management’s successful turnaround strategy while removing the execution risk associated with remaining listed. Although the Board remains confident the business could continue growing independently, it concluded that the certainty of an all-cash offer at an attractive premium represented the best outcome for shareholders. With irrevocable undertakings already covering more than 47% of the share register, the transaction appears well advanced towards completion.
What we are watching next: Publication of the Scheme Document, shareholder approvals and regulatory clearances ahead of the proposed completion.
Themes: Recommended Takeover | Alternative Finance | SME Lending | Mergers & Acquisitions
TIME Daily Candle Chart
Disclaimer:
All content is provided for general information only and should not be construed as any form of advice or personal recommendation. The provision of this content is not regulated by the Financial Conduct Authority.