


13th Aug 2026. 8.57am

Regency View:
BUY James Cropper (CRPR) Second Tranche

Regency View:
BUY James Cropper (CRPR) Second Tranche
Execution Is Starting To Deliver
Three months after our initial recommendation, James Cropper has delivered the first real evidence that its turnaround strategy is translating into improved financial performance. The latest full year results show a business that is becoming more profitable, generating stronger cash flow and steadily reducing debt, while management continues to invest in higher value growth opportunities across its specialist materials businesses.
The shares have responded accordingly, rising around 50% since our first tranche purchase. Normally, such a move would encourage caution, but in this case we believe the improving fundamentals justify the stronger share price. Rather than simply benefitting from a higher market rating, James Cropper appears to be growing into its valuation as operational execution continues to improve. For that reason, we believe this remains an attractive opportunity to add a second tranche to our position.

A turnaround gathering momentum
The latest results suggest that management’s turnaround programme is beginning to gain real traction.
Revenue increased to £102.9 million despite trading conditions remaining mixed across several end markets. More importantly, profitability improved sharply across almost every measure. Adjusted EBITDA increased by around one third to £8.9 million, adjusted profit before tax rose to £4.7 million and the company returned to statutory profitability with reported pre-tax profits of £3.9 million, compared with a loss in the previous financial year. Earnings per share also recovered strongly, moving from a loss of 55.9p to positive earnings of 30.8p.
Perhaps the most encouraging aspect of these results is the quality of the improvement. Management has spent the past two years simplifying operations, reducing costs, improving manufacturing efficiency and focusing investment on areas capable of generating higher long-term returns. Rather than relying on stronger demand alone, the latest figures suggest those internal improvements are now beginning to feed through into earnings.
Management also noted that results finished ahead of its own expectations, providing further confidence that the business is moving in the right direction.
Growth is becoming increasingly diversified
Another positive feature of the results is that the recovery is no longer dependent on a single division.
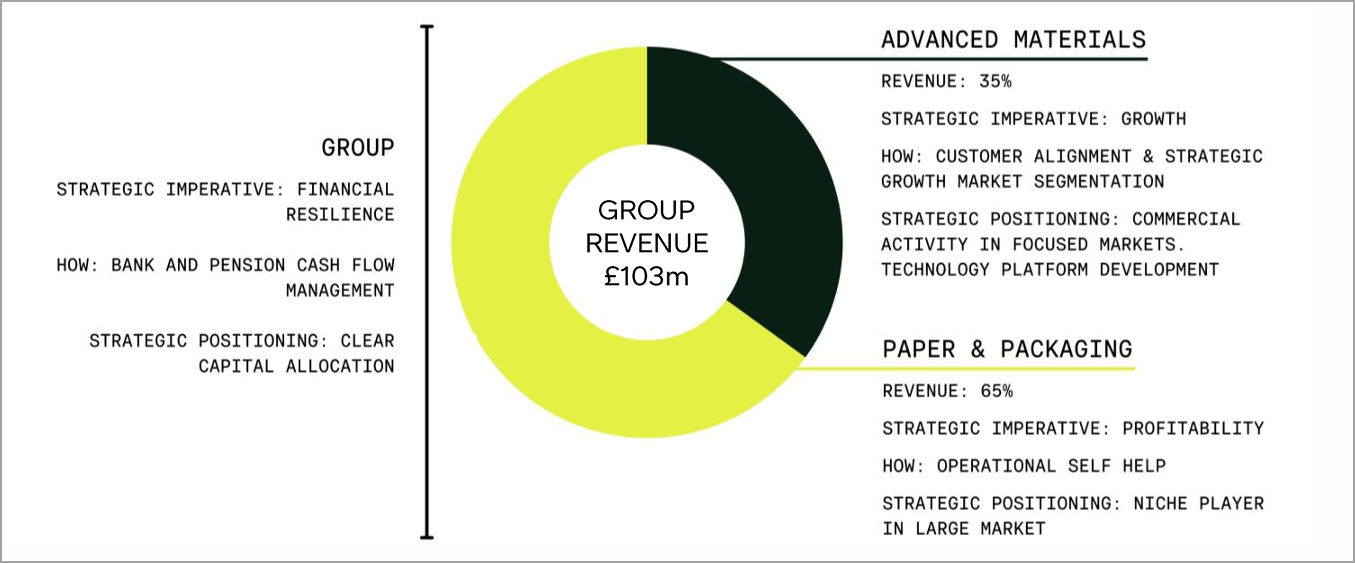
The Paper & Packaging business has shown encouraging resilience despite losing a significant merchant customer during the year. Through operational restructuring, improved production efficiency and tighter cost control, management was able to maintain broadly stable revenues while returning the division to positive EBITDA during the second half of the year. That represents an important milestone after several challenging years.
At the same time, Advanced Materials continues to establish itself as the group’s long-term growth engine. Revenue increased to a record level, supported by strong demand for hydrogen applications together with continued progress across aerospace, defence and industrial markets. The launch of UNIMAT, a new recyclable advanced materials platform, demonstrates that product innovation remains central to the group’s strategy as it expands into higher value specialist markets.
Management has understandably guided that hydrogen-related revenues may moderate following an exceptionally strong year. We view that as sensible guidance rather than a deterioration in the underlying opportunity. The broader structural drivers remain firmly intact, while increasing diversification across multiple end markets should help reduce dependence on any individual customer or industry over time.
Financial strength creates new opportunities
One of the biggest improvements has taken place away from the income statement.
Net debt reduced from £12.9 million to £8.1 million during the year, while cash balances increased to more than £13 million as improved profitability translated into stronger operating cash flow. The group’s leverage ratio has now fallen comfortably below one times EBITDA, leaving the balance sheet in a considerably stronger position than it was only twelve months ago.
Management has continued to build on that progress since the year end through a refinancing of its banking facilities, including a significant repayment of its principal term loan. While this attracted less attention than the earnings recovery, we believe it represents an equally important development.
A stronger balance sheet gives James Cropper considerably greater flexibility. It reduces financial risk, lowers interest costs and provides management with additional capacity to continue investing in new products, manufacturing capabilities and future growth opportunities. Businesses undergoing operational improvement often reach a point where stronger cash generation begins reinforcing further growth, and James Cropper increasingly appears to be approaching that stage.
The market is beginning to recognise the progress
The improving operational picture is now becoming visible on the share price chart.
Since our original recommendation in May, the shares have established a clear sequence of higher highs and higher lows while remaining comfortably above both the 50-day and 200-day moving averages. More recently, the shares have broken decisively above the previous resistance around 400p before holding those gains close to fresh twelve-month highs.
Importantly, the recent advance has not yet shown signs of becoming excessively stretched. Rather than immediately reversing lower after the breakout, the shares have remained well supported around the 450p level, suggesting investors are becoming increasingly comfortable with the improving fundamentals.
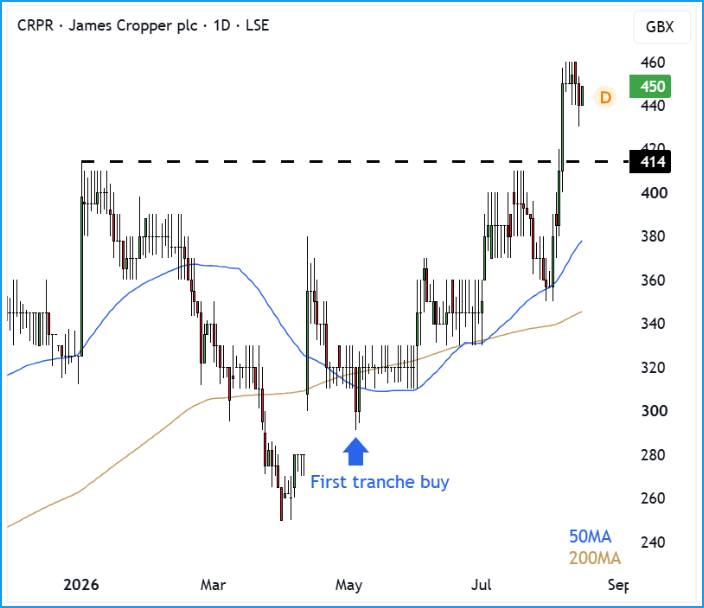
From a technical perspective, this remains a healthy long-term trend. The rising 50-day moving average continues to provide dynamic support above an upward sloping 200-day moving average, while the recent breakout demonstrates that buyers have been prepared to commit capital even after a strong recovery from last year’s lows.
Although some short-term consolidation would be perfectly normal following such a strong advance, the broader trend continues to support the improving fundamental story.
James Cropper is clearly a different business to the one we first analysed earlier this year. Profitability has returned, leverage has reduced, cash generation has strengthened and management continues to execute against the strategy it outlined during the turnaround. While the shares have already performed well, we believe that improvement has been driven by genuine operational progress rather than simply multiple expansion.
With a stronger balance sheet, improving earnings profile and several long-term growth opportunities still developing, we believe the investment case has become more compelling since our original recommendation. For that reason, we are adding a second tranche to our position.
Five key takeaways
1. Turnaround gaining traction: James Cropper has returned to profitability, with adjusted EBITDA, profit before tax and earnings all improving materially during the latest financial year.
2. More balanced growth: Both Paper & Packaging and Advanced Materials contributed positively, reducing reliance on any single division to drive future performance.
3. Balance sheet strengthening: Net debt has fallen sharply while cash generation has improved, giving management greater financial flexibility.
4. Technical trend remains supportive: The shares continue to trade above rising 50-day and 200-day moving averages after breaking out to fresh twelve-month highs.
5. Investment case strengthening: Three months after our initial recommendation, operational execution continues to improve, supporting our decision to add a second tranche to the position.
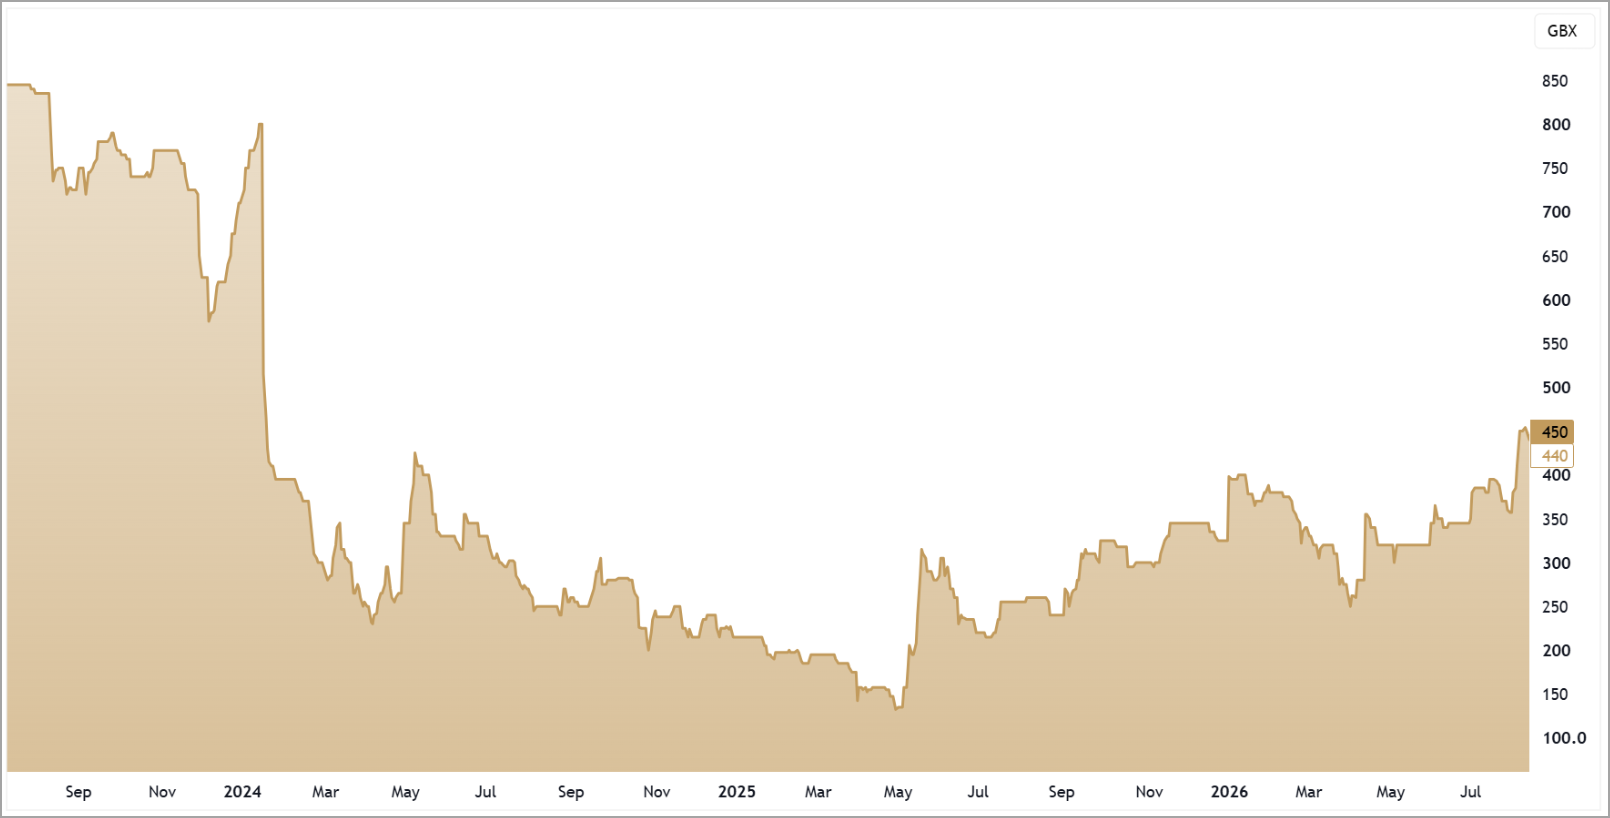
CRPR 3-Year Chart
Disclaimer:
All content is provided for general information only and should not be construed as any form of advice or personal recommendation. The provision of this content is not regulated by the Financial Conduct Authority.