


5th Nov 2026. 9.02am
Regency View:
BUY Franchise Brands (FRAN) Second Tranche

Regency View:
BUY Franchise Brands (FRAN) Second Tranche
Shifting Up a Gear
When we first recommended Franchise Brands in February 2025, the business had plenty going for it, but the share price was struggling to reflect those strengths. Management was still working through the integration of its acquisitions, debt remained a concern, and trading conditions across parts of Europe were proving difficult. We believed there was an opportunity for the shares to recover as those pressures eased.
Fast forward nearly 21 months, and we’re beginning to see that investment case develop. Franchise Brands (FRAN) has reported accelerating growth across its core businesses, management is making progress with its plans to simplify the group, and the shares are now challenging their highest levels of the past year.
Our original position, opened at 148.5p, is currently showing a gain of approximately 9%, excluding dividends. While that is a relatively modest return, we believe the improvement in the underlying business is becoming more significant than the share price performance alone suggests. With the latest trading update providing further evidence of progress, we’re adding a second tranche to our existing AIM Investor position.
The improvement is becoming harder to ignore
Franchise Brands reported another record quarter of system sales in its 3 November trading update, with growth accelerating to 8.4% during Q3. That compares with 6.7% in the first half and 4.2% in the corresponding quarter last year.
What makes these figures particularly encouraging is the breadth of the improvement. Rather than relying on one standout division to carry the group, several of its established businesses are now contributing more meaningfully.
The distinction between system sales and group revenue is worth keeping in mind. System sales represent the value of work undertaken across the franchise network, while Franchise Brands earns fees and other income from supporting that activity. Nevertheless, stronger system sales should provide a foundation for higher group earnings, particularly when the additional work can be handled without a corresponding increase in central costs.
Management has maintained its full-year adjusted EBITDA expectations of £36.5m to £38m, with market consensus at £37m. There has been no earnings upgrade, but the stronger third quarter provides greater confidence in achieving those forecasts.
Pirtek is doing more of the heavy lifting
One of the more significant developments has been the improvement at Pirtek, the group’s hydraulic hose replacement and maintenance business.
When we first recommended Franchise Brands, subdued industrial activity was weighing on parts of Pirtek’s European operations. The latest figures suggest those pressures are becoming more manageable.
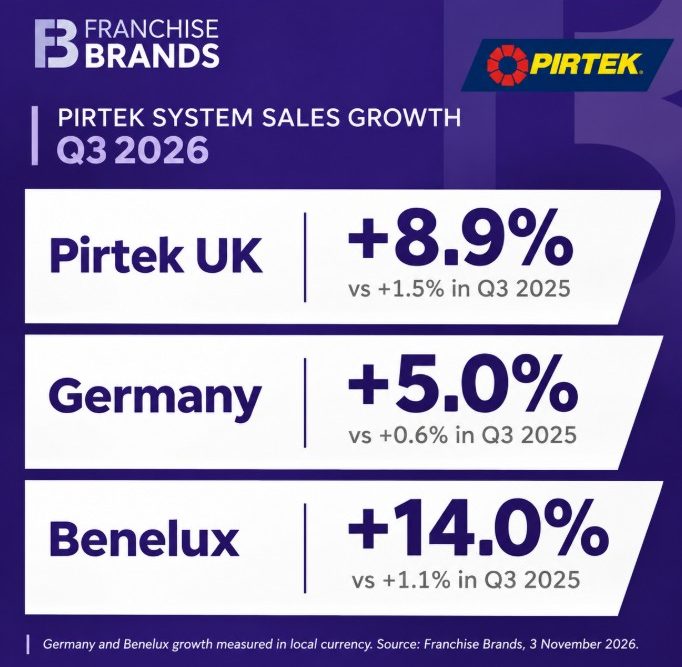
Pirtek UK, its largest market, delivered system sales growth of 8.9% in Q3, compared with just 1.5% a year earlier. Germany improved to 5% growth in local currency, while Benelux delivered 14%.
These are meaningful changes for an established business operating across mature markets. Management has been broadening Pirtek’s service offering and customer base, reducing its reliance on individual industries and creating more opportunities for repeat work.
We particularly like the reactive nature of much of Pirtek’s activity. When industrial equipment suffers a hydraulic failure, getting it working again is usually more important than delaying maintenance to save money. That does not make the business immune to economic weakness, but it provides a degree of resilience that more discretionary service providers often lack.
Filta has another route into its customers
North America continues to provide a second source of growth.
Filta International reported a 20.8% increase in system sales during Q3, supported by continued demand for its commercial kitchen services. Even excluding used cooking oil revenue, growth reached 15.9%, suggesting that the division’s performance is not simply a consequence of favourable commodity pricing.
Used cooking oil sales increased 42.3%, although much of that improvement came from higher prices rather than volumes. This distinction matters because oil prices can fluctuate, making them a less dependable source of earnings growth.
More encouraging is the early progress of FiltaClean Pro, a new service designed to expand the range of work Filta can undertake for commercial customers. The company has already secured its first national account with a leading quick-service restaurant group.
We see considerable value in expanding services through an established franchise network. Franchise Brands already has customer relationships, mobile technicians and operational infrastructure in place. Adding services that customers need regularly could increase revenue per relationship without requiring the business to build an entirely new network.
A simpler group could be a more profitable one
The other important development is management’s decision to concentrate on three core B2B franchise businesses: Pirtek, Filta and Metro Rod.
Franchise Brands has grown considerably through acquisitions, but that expansion has also introduced complexity and debt. The current strategy is less about adding further businesses and more about getting greater value from those already owned.
Management intends to simplify the portfolio, with any disposal proceeds directed towards reducing borrowings. This could make a meaningful difference to earnings, particularly as lower financing costs would allow more operating profit to reach shareholders.
Net debt has already declined from £83.3m in 2023 to approximately £61.6m on a trailing basis. Cash generation remains healthy, with trailing free cash flow of around 12.2p per share.
We would still like to see debt fall further. However, the combination of recurring franchise income, tighter working capital management and potential disposal proceeds gives management several ways to make progress.
The Water & Waste division remains a weaker area, with Q3 system sales growth of just 2.4%. Some projects at Willow Pumps have been deferred into the fourth quarter, and their eventual delivery will be worth monitoring.
The market is beginning to recognise the progress
At approximately 162p, Franchise Brands trades on around 16.5 times forecast FY26 earnings, falling to 14.9 times FY27 estimates. Consensus normalised earnings per share are expected to increase from 9.8p this year to 10.9p next year.
Those multiples are no longer as undemanding as when we first recommended the shares, but we believe they remain reasonable if operating momentum continues and debt reduction supports earnings growth.
There has also been some buying from within the boardroom. Chief Financial Officer Neil Miller purchased 15,000 shares across two transactions in August and October, investing just over £23,000 at an average price of approximately 154p. These are relatively modest purchases, but the timing is worth noting alongside the subsequent trading update.
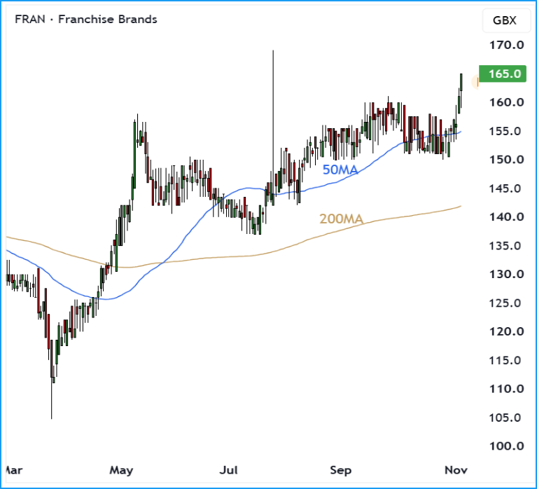
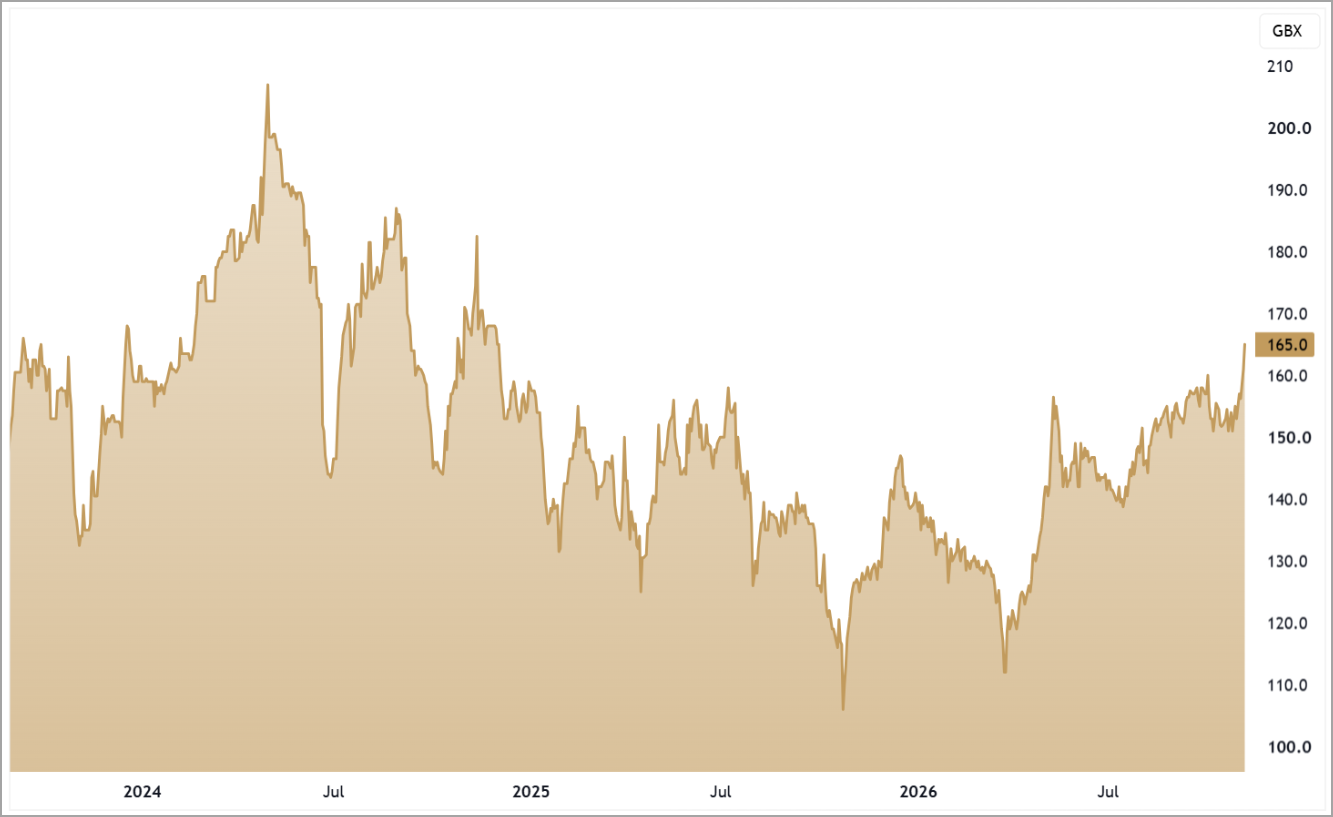
The technical picture has also improved considerably. After recovering from its April lows, FRAN established a sequence of higher swing highs and higher swing lows. More recently, the shares spent several weeks consolidating between approximately 151p and 160p, allowing the rising 50-day moving average to catch up with the price.
The shares are now testing resistance around 162p to 163p. A sustained move above this area would strengthen the case for another advance, although a short-term pullback remains possible after the recent rally.
Our original recommendation was based on the prospect of a recovery, and much of that investment case is now beginning to materialise. Pirtek is returning to stronger growth, Filta is finding new ways to expand, and management is concentrating on a simpler business with a healthier balance sheet. While the shares are no longer trading at the depressed levels we saw in February 2025, we believe the improvement in the underlying business justifies adding a second tranche to our AIM Investor position.
Five key takeaways
1. Accelerating growth: Group system sales increased 8.4% in Q3, with momentum improving across the core businesses.
2. Pirtek recovery: UK system sales growth reached 8.9%, supported by better performances across Europe.
3. North American expansion: Filta continues to grow strongly while broadening its service offering.
4. Debt reduction: A simpler business and strong cash generation could support further earnings growth.
5. Improving price trend: The shares are testing their annual highs following several weeks of consolidation.
FRAN 3-Year Chart
Disclaimer:
All content is provided for general information only and should not be construed as any form of advice or personal recommendation. The provision of this content is not regulated by the Financial Conduct Authority.