


10th Sep 2026. 9.17am
Regency View:
BUY Focusrite (TUNE)

Regency View:
BUY Focusrite (TUNE)
Ready for the Next Phase
A combination of rising margins, falling debt and improving trading is usually enough to get our attention. Add in a new generation of products built around proprietary tech, and the picture becomes more interesting. The key here is that these developments are arriving together, giving the business several ways to grow earnings without relying on a dramatic increase in sales.
The company is Focusrite (TUNE), a £160m AIM-listed audio group behind a collection of well-established brands used across music creation, recording and professional sound. Following several years of investment, the business is now starting to get more from that portfolio, while the shares trade at around 13 times forecast FY27 earnings. We think that combination of improving profitability, stronger cash generation and new product potential makes this a good time to take a closer look.
A collection of brands with room to grow
Focusrite will probably be best known for its Scarlett audio interfaces, the distinctive red boxes found in everything from bedroom recording setups to professional studios. But the group has developed into a much broader audio business, with eleven brands spanning music creation, recording and professional sound.
These are divided between two main divisions. Content Creation includes Focusrite, Novation, ADAM Audio, Sequential, Oberheim and Sonnox, selling audio interfaces, studio monitors, synthesisers, controllers and software. Audio Reproduction includes Martin Audio, Linea Research and TiMax, providing professional sound systems, amplification and immersive audio used at concerts, theatres and permanent installations.
What makes the model appealing is the opportunity to get more from these individual brands by putting the group’s wider infrastructure behind them. Focusrite can use established distribution relationships to expand smaller brands, share expertise and tech across the portfolio and increasingly deal directly with resellers and customers.
That final point is becoming particularly important. Focusrite has moved to a direct-to-reseller model in markets including the UK, Germany and Australia, with Japan recently added. Its direct-to-consumer operation is growing too, accounting for 12% of Content Creation revenue during the final six months of FY26.
Both routes bring Focusrite closer to its customers while allowing it to capture more of the margin on each sale. Having spent years building the portfolio, there is now plenty of scope to get more from what it already owns.
Modest growth hides a better performance
Focusrite’s latest accounts require a little untangling because the company changed its financial year end, leaving the statutory figures covering 18 months. The cleaner comparison is management’s pro-forma twelve months to February 2026.
Revenue increased 1.3% to £164.6m, or 2.7% on an organic constant currency basis. Adjusted EBITDA grew rather faster, rising 5.7% to £24.7m, while adjusted operating profit edged higher to £15.1m.
There was more going on beneath the group numbers. Content Creation delivered organic constant currency growth of 3.6%, with the core Focusrite brand growing 9.0% and Sonnox 24.7%. Adjusting for US sales that had been brought forward into the previous period ahead of anticipated tariffs, management puts underlying Content Creation growth at 9.5%.
Audio Reproduction was broadly flat, but that compares with a wider market management believes declined by mid-to-high single digits. The Americas were particularly strong, with organic constant currency growth of 10.8%.
None of this suggests Focusrite is suddenly becoming a high-growth business. What it does suggest is that the tougher conditions of recent years are easing at the same time as the company is becoming more efficient.
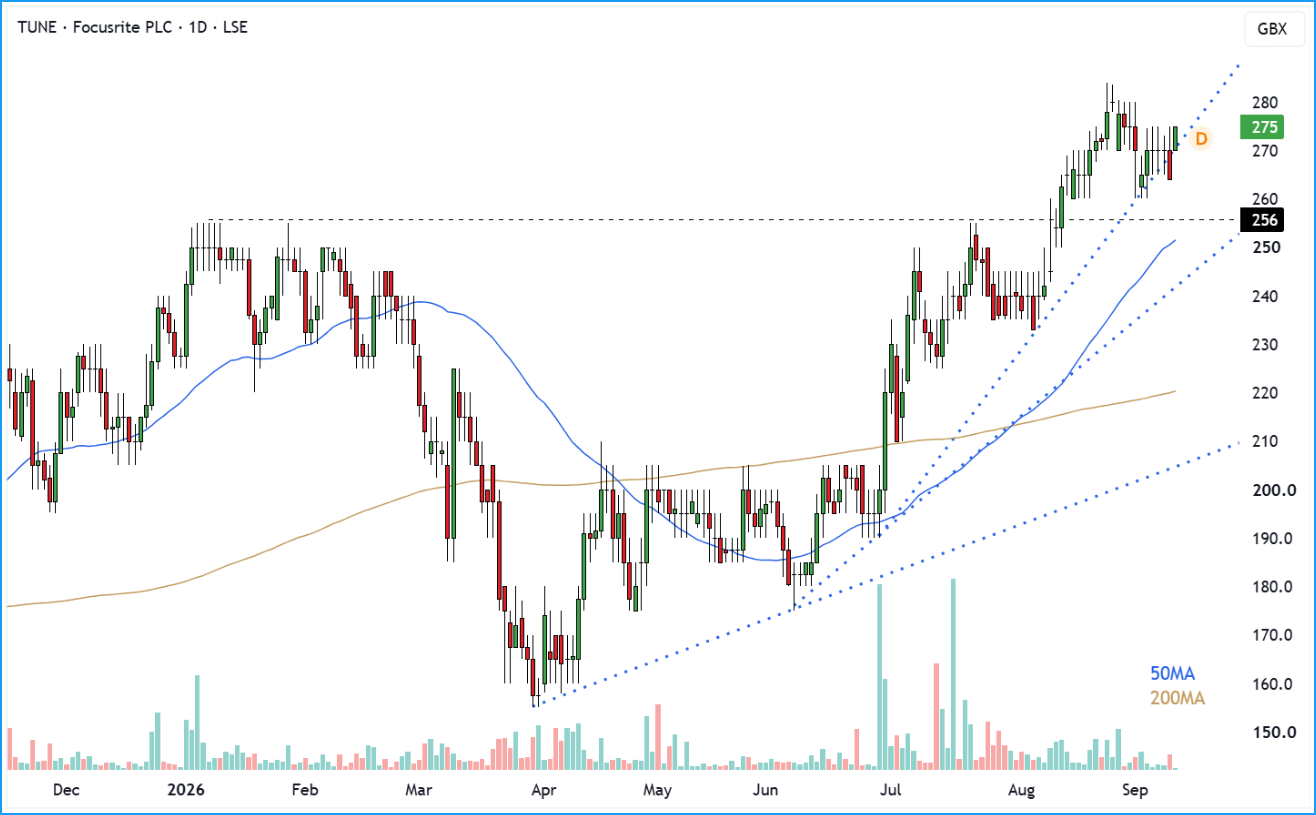
Recent share price performance has been strong
The margin opportunity
This is where we think the numbers become more compelling.
Group gross margin increased from 43.4% to 45.1% last year, while Content Creation improved from 42.8% to 45.9%. Pricing helped offset tariffs, but Focusrite is also benefiting from production efficiencies and changes to the way it sells its products.
The growing direct-to-consumer business and move towards direct reseller relationships should help that process continue. Management has also completed a restructuring programme expected to generate more than £1.4m of annualised savings.
The early evidence of operating leverage is already there. Revenue increased just 1.3% last year while adjusted EBITDA grew 5.7%. If Focusrite can combine continued sales growth with further margin progression, profits have the potential to move considerably faster than the top line.
Cash generation gives us some additional comfort. Underlying free cash inflow reached £12.9m, helping net debt fall from £17.9m to £8.6m. Working capital also improved as inventories and receivables moved back towards more normal levels.
Development spending remains significant, with £11.2m capitalised during FY26, so we’ll keep a close eye on cash conversion. But reducing debt while continuing to invest heavily in new products is a decent place to be.
Bringing its own tech to market
Some of that investment has been going into Focusrite’s new proprietary silicon platform, FAESIC.
The idea is to create a common tech foundation that can be used across future Content Creation products. Bringing more of this capability in-house should give Focusrite greater control over product development, reduce its reliance on third-party silicon and allow the same underlying tech to be deployed across multiple products.
The development work is now approaching the point where investors can start seeing what it produces. The first product incorporating FAESIC is scheduled for launch during FY27, with further products planned over the following three years and beyond.
It is too early to attach a value to FAESIC in isolation, but we like the direction. If Focusrite can reuse its own tech across a growing range of products, there are potential benefits for both development efficiency and margins.
Current trading adds confidence
The timing of our recommendation also benefits from having a more recent read on trading.
Focusrite said in August that trading during the opening months of FY27 remained ahead of the previous year, with healthy underlying demand across both divisions. Full-year expectations were unchanged, with the company citing analyst forecasts of £170.1m-£173.7m of revenue and £25.2m-£27.4m of adjusted EBITDA.
Consensus currently points to EPS of around 20.5p for FY27, putting the shares on roughly 13 times forecast earnings at our 269p recommendation price.
There are still weak spots. Sequential has suffered from softer premium synthesiser demand and was subject to a £9.8m impairment last year, while tariffs and consumer spending remain risks. The shares have also rallied strongly from their lows, so we’re not arriving before anyone else has noticed the improvement.
Even so, we think the valuation leaves enough room for further progress if Focusrite delivers on current expectations. Improving margins, lower debt, healthier trading and the first products from its new tech platform give the business several ways to move forward from here.
Five key takeaways
1. Margins are recovering: Group gross margin increased from 43.4% to 45.1%, giving profits scope to grow faster than sales.
2. Current trading is encouraging: FY27 has started ahead of last year, with healthy underlying demand across both divisions.
3. Debt is coming down: Strong cash generation helped reduce net debt from £17.9m to £8.6m.
4. New tech is approaching launch: The first product using Focusrite’s proprietary FAESIC platform is due during FY27.
5. The valuation leaves room for progress: At around 269p, Focusrite trades on roughly 13 times forecast FY27 earnings.
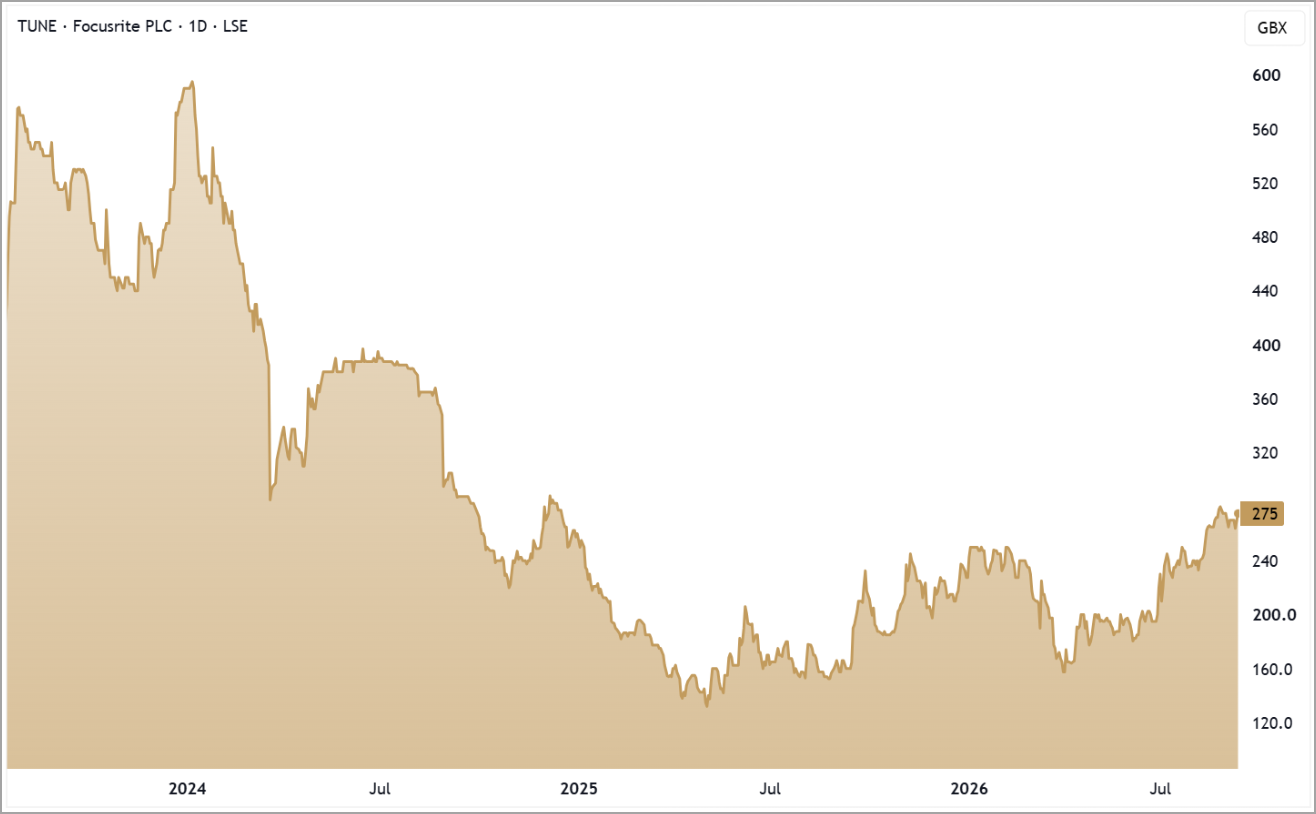
TUNE 3-Year Chart
Disclaimer:
All content is provided for general information only and should not be construed as any form of advice or personal recommendation. The provision of this content is not regulated by the Financial Conduct Authority.