


24th Sep 2026. 9.09am
Regency View:
BUY RWS Holdings (RWS) Second Tranche

Regency View:
BUY RWS Holdings (RWS) Second Tranche
RWS: Finding its Place in the AI Boom
AI has already created some spectacular winners, but the next phase of the opportunity will not necessarily belong only to the companies building the models. As businesses move from experimenting with AI to actually using it across their operations, they need vast quantities of reliable data, specialist knowledge and systems that can make AI-generated content accurate, secure and usable across different languages and markets.
That brings us back to RWS Holdings (RWS). We first recommended the shares in 2023 and our original position is currently down around 50%, so there is no disguising the fact that this has been a disappointing investment so far. But we have deliberately resisted the temptation to average down simply because the shares became cheaper. Instead, we have waited for evidence that the business itself is moving in the right direction. We think that evidence is now beginning to arrive, and we’re adding a second tranche.
A different RWS is beginning to emerge
RWS has traditionally been associated with translation and localisation, helping some of the world’s largest companies adapt content, products and intellectual property for different countries and languages. It remains a significant part of the business, but management is now repositioning the group around a much broader opportunity created by AI.
The business is split into three divisions. Generate helps companies create and organise content and data, Transform covers localisation and translation, while Protect provides intellectual property services. Importantly, RWS already works with more than 80 of the world’s top 100 brands, giving it relationships with precisely the sort of large organisations now working out how to deploy AI safely across international markets.
This is where RWS has an opportunity to occupy an interesting position in the AI ecosystem. Large language models can generate and translate enormous amounts of content, but global companies still need that output to be accurate, culturally appropriate, secure and consistent with their own terminology and brand.
RWS is increasingly building the tech to sit between the AI model and the enterprise customer, while combining it with the language expertise and specialist data it already has.
AI is becoming a real source of growth
There is now some financial evidence behind that strategy.
AI-related products and services accounted for 32% of group revenue during the first half, up from 26% a year earlier. Generate was the standout performer, with revenue climbing 45% to £99.4m and organic constant-currency growth reaching 52%.
Much of that came from TrainAI, which helps companies train and refine AI models. Its work includes data annotation, human feedback, safety and bias testing and synthetic data validation. RWS won two significant new clients during the half, including a global tech customer that had already started generating revenue, with another win expected to contribute during the second half.
There is an important caveat. Some of TrainAI’s exceptional growth came from a large additional programme with an existing customer, so we shouldn’t simply extrapolate 52% growth indefinitely.
What matters more is that RWS is demonstrating that AI can create new demand for its expertise rather than simply replacing the translation work on which the business was built.
Building the tech around the expertise
RWS is also investing in its own AI products.
Language Weaver Pro launched earlier this year in partnership with enterprise AI specialist Cohere. It is designed for business-critical translation, where accuracy, security and control matter rather more than asking a general-purpose chatbot to have a go. Initial customer deals had already been signed by June and were expected to begin contributing revenue during the second half.
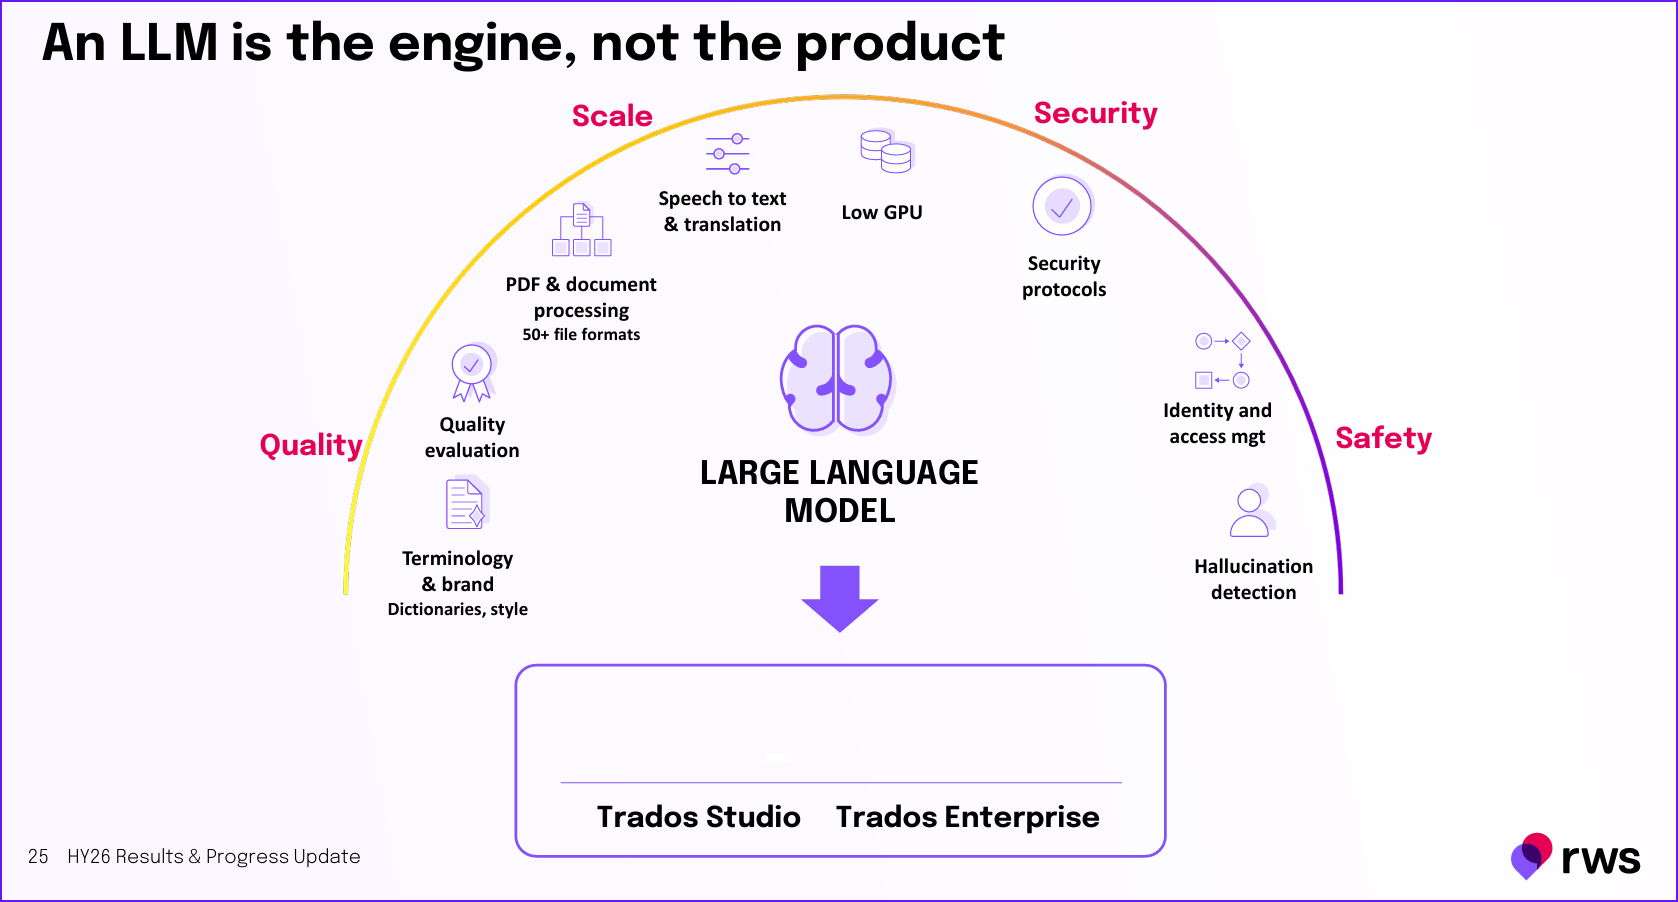
The graphic below explains rather neatly where RWS believes it can add value. As management puts it, “an LLM is the engine, not the product”. For a large organisation, the model still needs to sit alongside security controls, quality evaluation, company terminology, document processing and safeguards against hallucinations.
Why a large language model (LLM) alone isn’t enough
This is the longer-term opportunity we find particularly compelling. RWS doesn’t need to build the next ChatGPT. Its opportunity lies in helping large organisations make AI useful across different languages, cultures and specialist areas where accuracy and security matter.
The numbers are starting to follow
The first-half results in June provided the strongest evidence so far that the wider business is improving.
Revenue increased 5% to £360.3m, or around 7% organically at constant currencies. Adjusted EBITDA rose 20% to £45.7m, adjusted profit before tax increased 33% to £24m and adjusted EPS climbed 34% to 4.9p.
Not everything is growing. Transform remains the largest division and its revenue fell 4.6% organically to £210.1m as RWS continues moving it towards a more tech-led model. Encouragingly, adjusted operating profit still increased from £8.7m to £10.2m as efficiency improvements and lower overheads offset some of that pressure.
Cash generation remains healthy too. Operational free cash flow was £30.4m during the half, although conversion fell from 92% to 67%. Net debt stood at a manageable £32.5m at the end of March, before the subsequent acquisitions.
Expanding the opportunity
Management hasn’t stood still since those June results.
In August, RWS agreed to acquire Acolad, a European language and content business with £182m of 2025 revenue, for an enterprise value of just £22.4m. Acolad works with approximately half of the CAC 40 and derives around half its revenue from regulated industries.
The attraction goes beyond buying additional revenue cheaply. RWS intends to take its AI platforms, including Language Weaver Pro and its developing Transform products, into Acolad’s much larger European enterprise client base. If management can execute that cross-selling strategy, the acquisition could give its AI products a considerably wider route to market.
There is integration risk and Acolad itself needs work, so we aren’t building the investment case around assumed synergies. But at the price being paid, we think the potential reward is attractive.
Why we’re buying again now
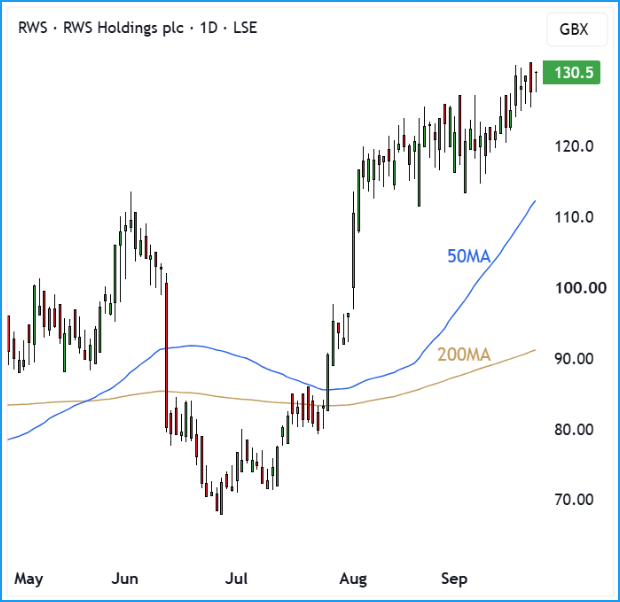
The shares themselves are finally beginning to reflect the improvement. After bottoming below 70p during the summer, RWS has broken above its June high and is now trading around 129p. The 50-day moving average is rising strongly, the shares are comfortably above the 200-day average and the sequence of higher highs and higher lows remains intact.
That means we’re adding after a substantial rally rather than trying to pick the bottom. We’re comfortable with that. Our original position demonstrates rather neatly why cheap shares can always get cheaper, and we would rather commit additional capital after the business and share price have started confirming the thesis.
There is still plenty to prove. The next trading statement is due towards the end of October and should give us our first meaningful update since June on whether the stronger trading has continued. In particular, we’ll be watching TrainAI, early adoption of Language Weaver Pro and progress within Transform.
For newer AIM Investor members, we also think the investment case stands on its own at today’s price. RWS is not yet a pure AI growth business, and we don’t think it should be valued as one. But AI is becoming a larger part of what it does, earnings are improving and management is building products designed to address a potentially much larger long-term market.
Five key takeaways
1. AI is becoming meaningful: AI-related products and services increased from 26% to 32% of group revenue during the first half.
2. Generate is growing rapidly: Revenue increased 45%, helped by strong demand for TrainAI and new client wins.
4. Profits are recovering: Adjusted EBITDA rose 20% and adjusted profit before tax increased 33% in H1.
5. The opportunity is getting larger: Acolad provides another substantial European enterprise client base for RWS’s developing AI platforms.
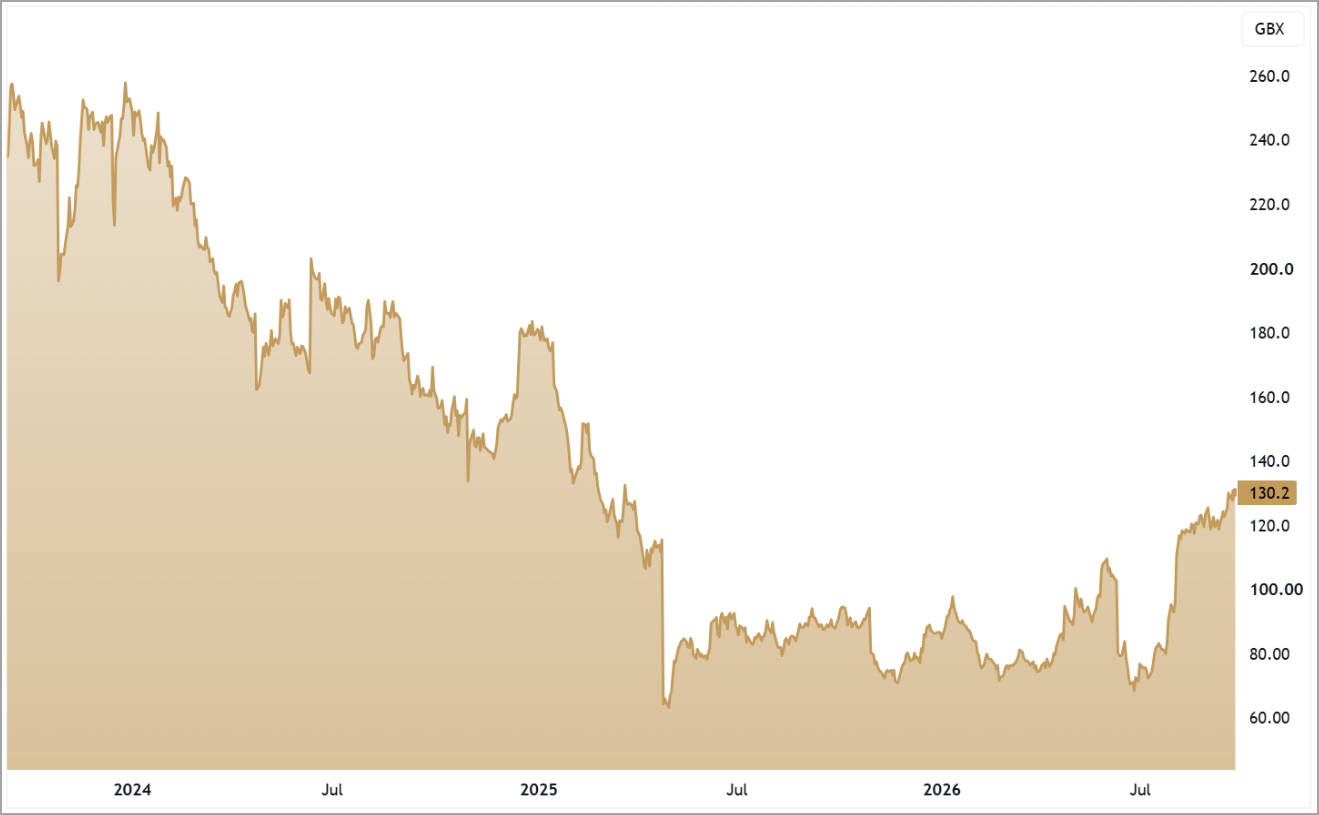
RWS 3-Year Chart
Disclaimer:
All content is provided for general information only and should not be construed as any form of advice or personal recommendation. The provision of this content is not regulated by the Financial Conduct Authority.