


27th Aug 2026. 8.57am
Regency View:
BUY Colefax Group (CFX)

Regency View:
BUY Colefax Group (CFX)
Quality Growth Without the Premium Price
Colefax is unlikely to be a familiar name to many investors, but there is plenty to like beneath the surface. The AIM-listed group sits at the luxury end of the interiors market, designing and distributing furnishing fabrics and wallpapers through brands including Colefax and Fowler, Cowtan & Tout, Jane Churchill, Manuel Canovas and Larsen. It also operates smaller furniture and interior decorating businesses.
What has caught our attention is the combination of improving profits, excellent cash generation and a share price that has been steadily moving higher. Colefax has just reported a record year, yet the shares continue to trade on around ten times historic earnings. With the core US business performing particularly well and a substantial cash balance providing plenty of financial flexibility, we believe the current valuation leaves room for further progress.
America takes centre stage
Colefax generated revenue of £115.9m in the year to 30 April 2026, an increase of 5.4%, or 7.3% at constant exchange rates. Profit growth was considerably stronger, with pre-tax profit climbing 18.3% to £10.53m and earnings per share increasing 29.8% to 140.7p.
The real engine of the business is the Fabric Division, which accounts for around 90% of group turnover. Sales here increased 8.4% to £104.0m and were 10.7% higher at constant currency. More impressive was the effect on profitability, with divisional pre-tax profit increasing 33.4% to £10.62m. That tells us there is meaningful operational gearing in the business, with additional revenue capable of producing a much larger increase in profit.
America is increasingly important to this performance. The US now represents 63% of Fabric Division turnover, with sales increasing 15.9% at constant currency during the year. Even after stripping out tariff surcharges, underlying US sales were 10.2% higher. This followed constant-currency growth of 12.9% in the previous year, so this is not simply a favourable comparison against a weak period.
There are encouraging signs that this momentum has continued. When the results were published at the end of July, management said US sales had remained strong since year-end and expressed cautious optimism that this would continue for at least the first half of the current financial year.
Plenty left after paying the bills
One of the features we particularly like about Colefax is the amount of cash being produced alongside the improvement in profits.
Cash generated from operations increased to £18.48m during FY26, while net cash inflow from operating activities reached £15.14m. Capital expenditure was only £2.43m, leaving the group with substantial surplus cash generation. Colefax subsequently finished April with £23.55m of cash, compared with £22.31m a year earlier.
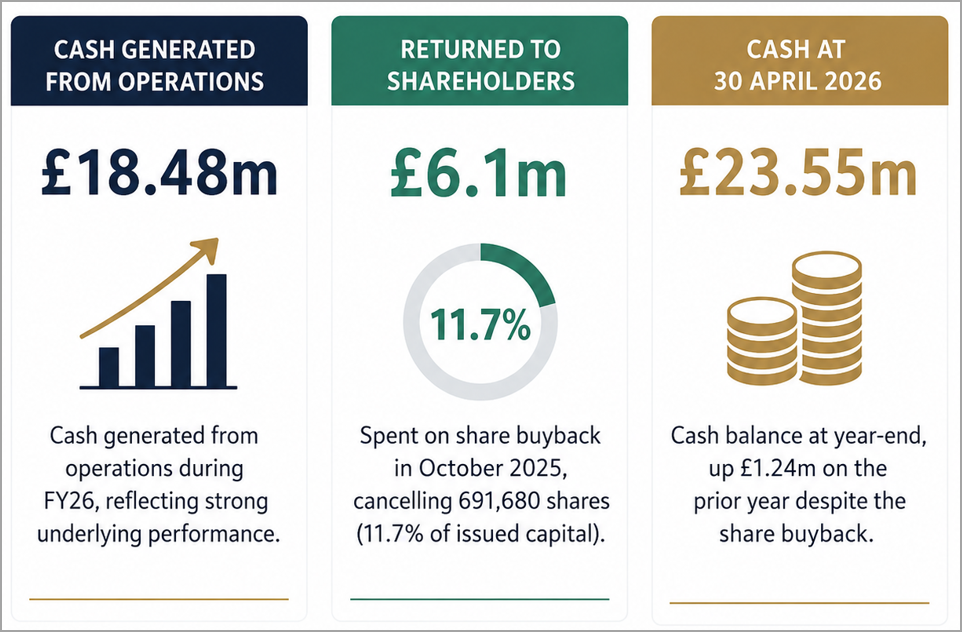
That might not sound extraordinary until we consider what happened in between. In October, Colefax spent £6.1m buying back and cancelling 691,680 shares through a tender offer. That represented 11.7% of its issued share capital, meaning the company was able to make a sizeable return of surplus capital while still ending the financial year with more cash on the balance sheet.
The lower share count has contributed to the particularly strong growth in earnings per share, so we shouldn’t attribute the entire 29.8% increase to underlying profit growth. Nevertheless, buying back a meaningful proportion of the company without weakening the balance sheet is an attractive use of surplus capital when the shares are sensibly valued.
Not everything is travelling in the same direction
There are weaker areas of the business and these are worth recognising.
Colefax’s Decorating Division had a difficult year, with revenue falling 21.1% to £8.86m and the division recording a pre-tax loss of £339,000. Its UK furniture operation also experienced pressure. Kingcome sales increased 8%, but pre-tax profit fell 30.6% and its year-end order book was 27% below where it started the year.
Both reflect difficult conditions at the luxury end of the UK market, where high transaction costs, relatively high interest rates and uncertainty surrounding taxation have weighed on activity. The good news is that these businesses are considerably smaller than the Fabric Division, while management expects Decorating to return to profitability this year.
There is also an unusual sensitivity investors need to understand. Management believes demand for its luxury products in America is closely correlated with the US stock market and specifically identifies a significant market correction as the principal external risk to US sales. With America now such an important source of profit, a prolonged deterioration in spending among wealthy US customers would undoubtedly change the picture.
A sensible price for a business doing well
After such a strong run in the shares, we might expect valuation to be the sticking point. Instead, this is one of the attractions.
At 1,410p, Colefax trades on almost exactly ten times the 140.7p of earnings generated during FY26. That doesn’t strike us as demanding for a company that has just increased pre-tax profit by 18.3%, generated more than £15m of operating cash flow and ended the year with £23.5m of cash.
The dividend is modest, with the proposed 3.3p final payment taking the full-year dividend to 6.3p, up 7%. Income is therefore not the reason for owning the shares. We are much more interested in the company’s ability to reinvest in its brands and distribution network while returning excess capital through buybacks.
Letting the trend do some of the work
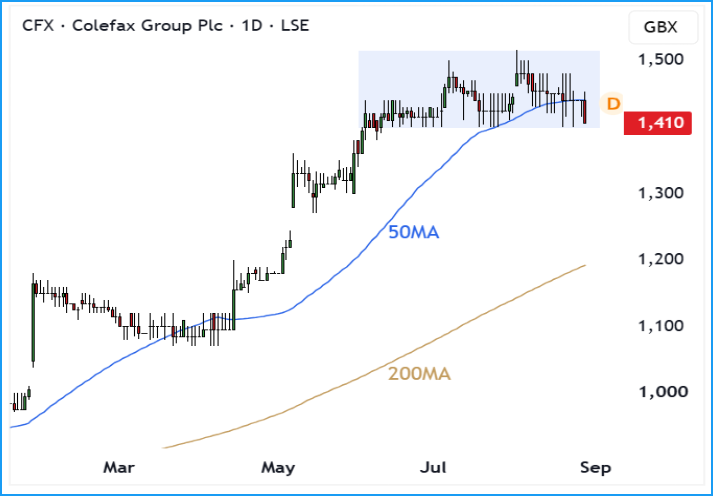
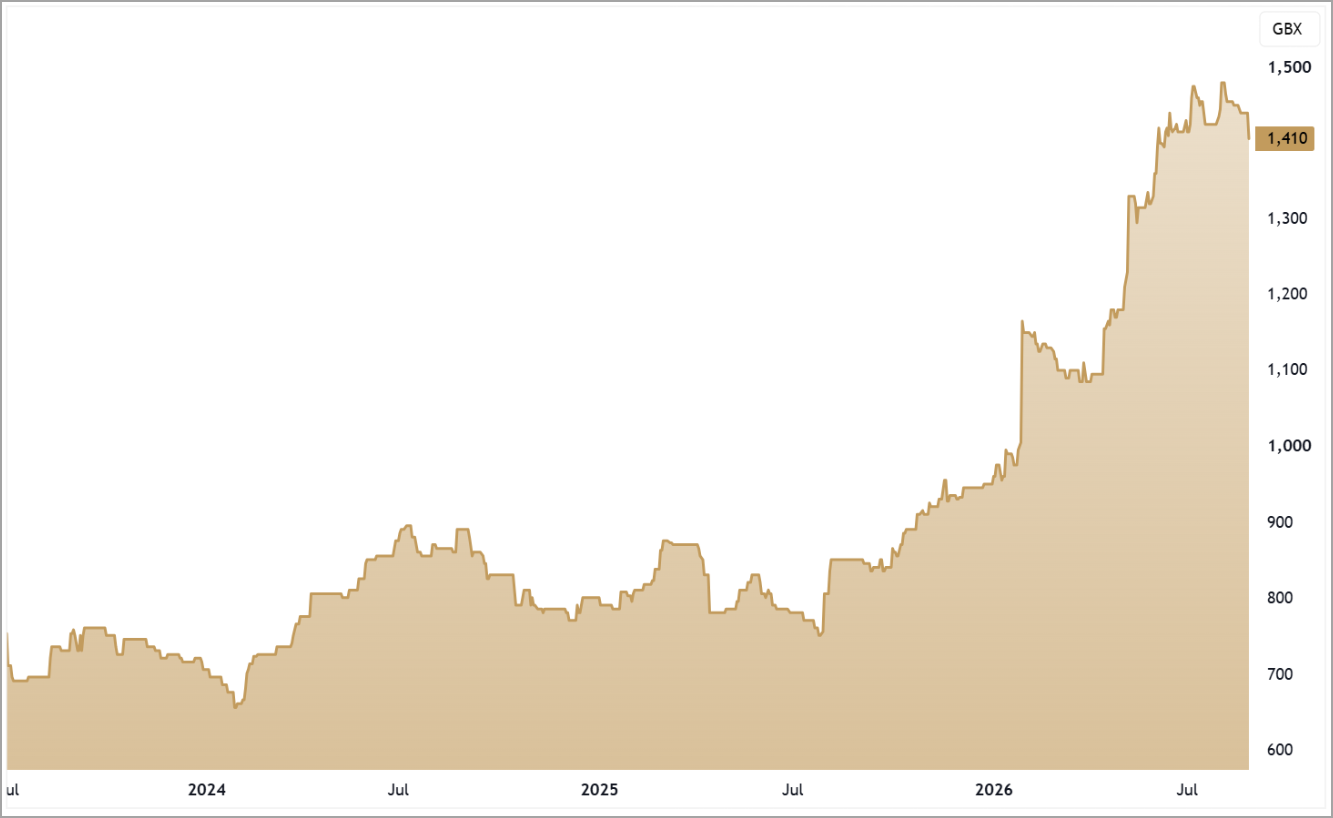
The chart adds another dimension to the investment case. Colefax shares have advanced from below 800p last summer to around 1,410p today, establishing a clear sequence of higher highs and higher lows along the way.
Importantly, we’re not buying immediately after another sharp vertical move. Following the latest push towards 1,500p, the shares have spent several weeks consolidating, allowing the rising 50-day moving average to catch up with the price. The much slower 200-day moving average continues to rise well beneath the market, leaving the broader trend firmly pointed higher.
Liquidity does require some care. Colefax is a relatively small AIM company and the bid-offer spread can be wide, so this is a stock where limit orders and patience make sense rather than chasing the market.
For us, the attraction is the combination rather than any single number. Colefax has strong momentum, but we’re not being asked to pay a momentum-stock valuation. It has value characteristics, but we’re not waiting for a struggling business to turn around. Instead, we are buying into a profitable, cash-generative company whose most important market is growing strongly while the shares remain reasonably valued.
Five key takeaways
1. US growth driving performance: Strong trading in the US continues to underpin the Fabric Division, with sales growth translating into a much faster increase in divisional profits.
2. Cash generation remains strong: Colefax continues to produce substantial cash, ending the year with £23.5m despite returning £6.1m to shareholders through its tender offer.
3. Shareholders benefiting from buybacks: The cancellation of 11.7% of the issued share capital has reduced the share count significantly and contributed to strong growth in earnings per share.
4. Valuation remains reasonable: Despite the strong share-price performance, Colefax trades on around ten times FY26 earnings, leaving the valuation relatively modest given current trading.
5. Trend remains firmly positive: The shares remain in a well-established uptrend and are now consolidating around the rising 50-day moving average after their recent move towards 1,500p.
CFX 3-Year Chart
Disclaimer:
All content is provided for general information only and should not be construed as any form of advice or personal recommendation. The provision of this content is not regulated by the Financial Conduct Authority.