


7th Aug 2026. 10.02am

Weekly Briefing – Friday 7th August
| Market | Movement this week (%)* |
|---|---|
| FTSE 100 | +0.19% |
| FTSE 250 | +2.95% |
| FTSE All-Share | +0.51% |
| AIM 100 | +4.42% |
| AIM All-Share | +3.40% |
* Price movement from Monday's open at 8am
Regency View:
Weekly Briefing – Friday 7th August
Market Overview
Dear Investor,
There comes a point in every rally where investors stop asking whether the market has gone too far and start asking whether they’ve been too cautious.
That feels a little like where we are today.
Over the past week we’ve seen the S&P 500, Germany’s DAX and the STOXX Europe 600 all climb to fresh record highs. Here in the UK, the FTSE 100 hasn’t quite joined the party, but it continues to trade just beneath its own highs, quietly building pressure rather than showing any real desire to move lower.
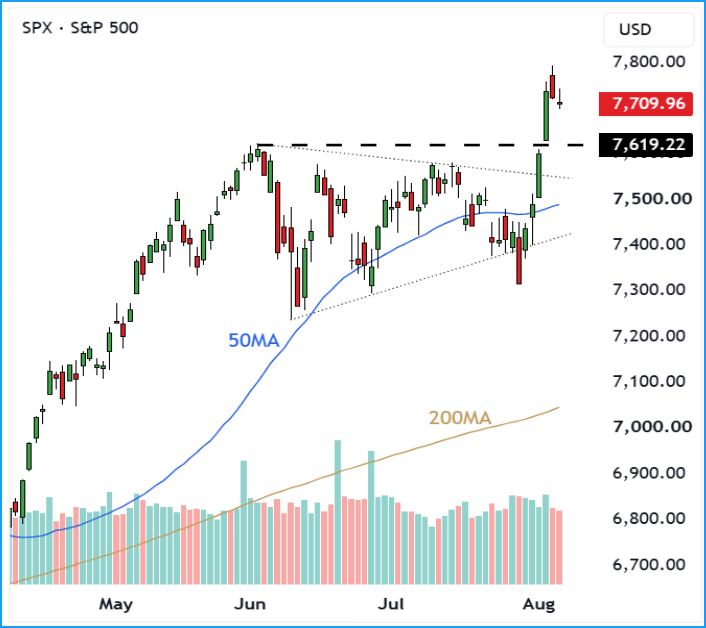
What’s changed isn’t the news flow, it’s what the market has chosen to focus on. A few weeks ago every conversation revolved around oil prices, inflation and whether central banks might be forced back into raising interest rates. Those risks haven’t disappeared, but they’ve been pushed down the list as company earnings have started doing the talking.
The reporting season has been encouraging on both sides of the Atlantic. In the US, companies have been beating expectations at one of the strongest rates we’ve seen for several years, while Europe’s earnings have also been holding up well. Perhaps more importantly, the strength is beginning to broaden out. This no longer feels like a rally being dragged higher by a handful of technology stocks. Industrials, financials and other cyclical areas are increasingly pulling their weight, which generally makes for a healthier backdrop.
For UK investors, that’s worth paying attention to. The FTSE may not have broken to fresh highs yet, but many of its largest constituents generate the bulk of their earnings overseas. If global earnings continue to surprise positively, the UK market doesn’t necessarily need a domestic catalyst to participate.
Markets have a habit of reaching new highs when the news still feels uncomfortable. That’s because share prices don’t move on today’s headlines, they move on tomorrow’s earnings. Right now, the market seems increasingly comfortable that those earnings are still moving in the right direction.
Wishing you a great weekend,
Tom
Thomas Light – Chartered FCSI
Director of Research
Market Movers
On the rise: Travis Perkins (LSE: TPK) +20.1% on the week
Travis Perkins moved higher after delivering resilient half-year results that suggested its turnaround strategy is beginning to gain traction despite a difficult backdrop for the UK construction market.
Group revenue slipped 1.8% to £2.26 billion as weaker volumes offset building materials price inflation, but adjusted operating profit excluding property gains held steady at £62 million. More encouragingly, adjusted earnings per share rose 13.5% to 15.1p, while the balance sheet continued to strengthen. Net debt has been transformed into a £55 million net cash position before leases, giving the group greater financial flexibility ahead of any recovery in construction activity. Management also highlighted early progress in improving profitability within its core General Merchant business through better pricing discipline, procurement savings and an improved sales mix, while Toolstation UK continued to grow both revenues and margins.
The results mark the first meaningful update under new Chief Executive Gavin Slark, who joined the business in January. Rather than promising a quick recovery, the focus appears to be on rebuilding operational discipline, strengthening customer relationships and ensuring the business is well positioned when market conditions improve. While demand across housebuilding remains subdued, infrastructure-related activity has proved more resilient, helping offset some of the weakness elsewhere.
Regency View: This wasn’t about a sudden recovery in trading; it was about evidence that management is improving the business despite difficult conditions. With a much stronger balance sheet and early signs that margins are moving in the right direction, Travis Perkins looks increasingly well placed to benefit when activity across the construction sector eventually picks up.
Prudential came under pressure after reports that Chinese tax authorities had begun applying a 20% personal income tax to income earned from certain offshore insurance policies, raising concerns over future demand from mainland Chinese customers buying policies in Hong Kong.
That matters because Hong Kong remains one of Prudential’s most important markets, with mainland visitors an important source of new business. Offshore policies have historically appealed to Chinese customers looking for broader investment options, multi-currency exposure and greater diversification, so any reduction in their relative tax advantage naturally raises questions over future sales growth. The concern spread across the sector, with AIA and other Hong Kong-focused financial groups also falling sharply.
There is still plenty of uncertainty around how widely the tax will be applied and how customers will respond. Some analysts have argued that the sell-off may be overdone because the broader reasons for buying Hong Kong insurance remain intact, while others expect the shares to carry an overhang until investors have greater clarity on the regulatory direction.
Regency View: This is a genuine headwind, but not one that fundamentally changes Prudential’s long-term growth story across Asia. With demand for offshore diversification still intact, the key question is whether the new tax meaningfully alters customer behaviour or simply takes some of the shine off an otherwise attractive proposition.
Sector Snapshot
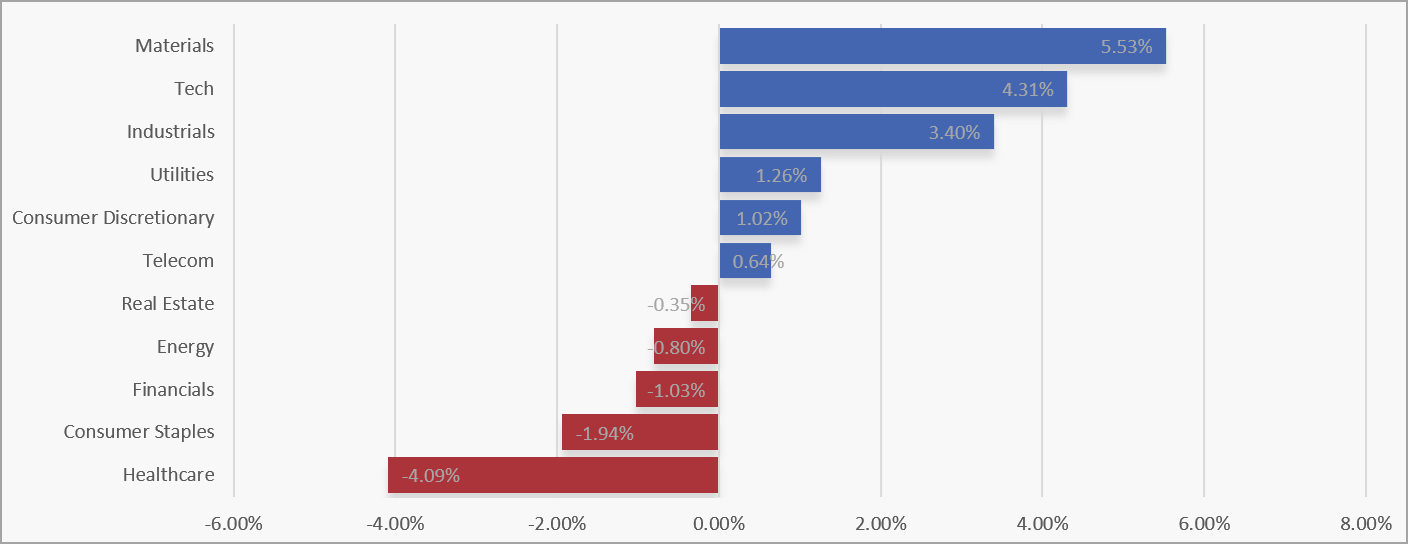
Materials led the UK market this week as mining stocks staged a strong recovery, while Technology and Industrials also delivered impressive gains. The leadership from these economically sensitive sectors points to a more positive tone across the market, with investors rotating back into areas that had previously lagged.
Healthcare was the weakest-performing sector by some distance, while Consumer Staples and Financials also came under pressure. Energy slipped modestly despite its recent strength, suggesting investors were increasingly favouring growth and cyclical sectors over the more defensive areas of the market.
UK Sector Performance (7-Days)
UK Price Action
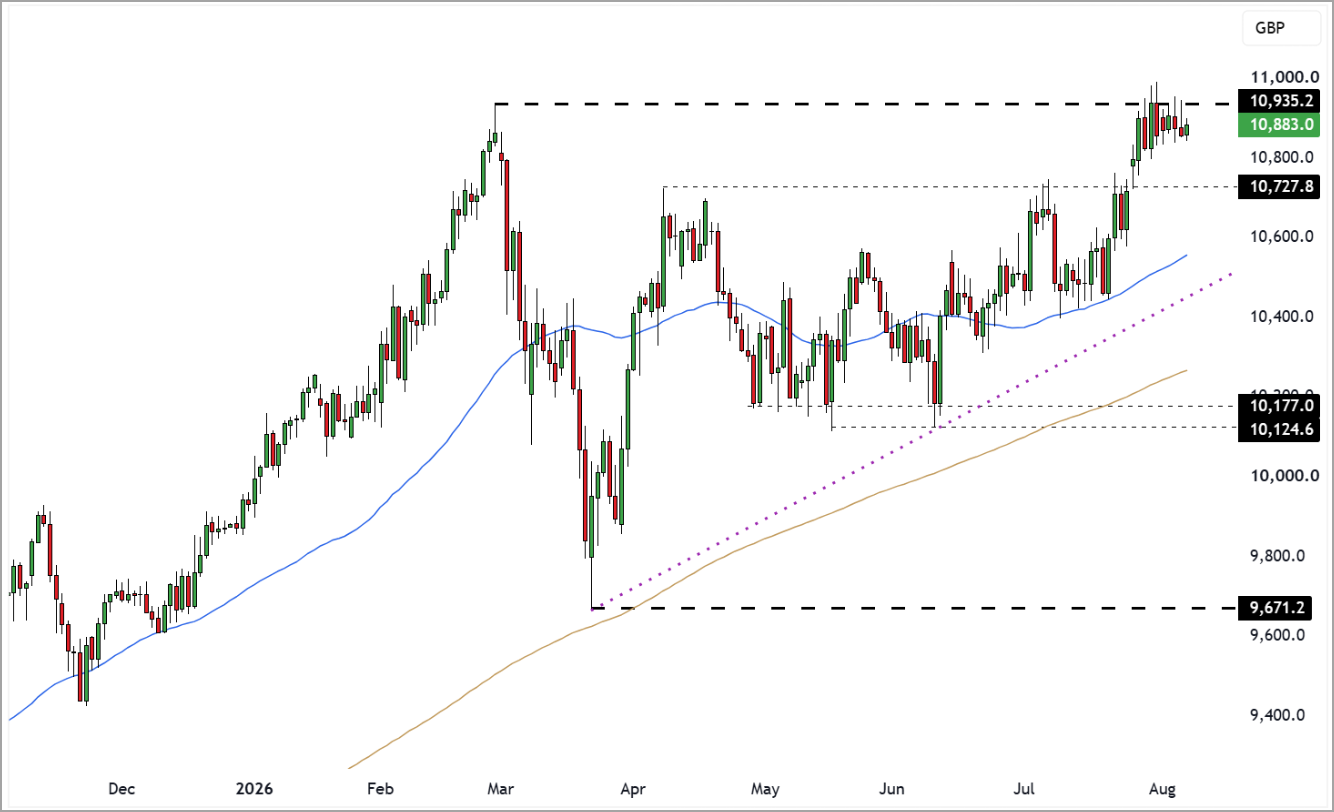
The FTSE has spent the week coiling just beneath its all time highs, with price action tightening rather than being rejected from resistance. That distinction matters. After such a strong recovery, sellers have so far been unable to force the market meaningfully lower, while buyers continue to absorb supply close to the February peak. A clean break above this area would push the FTSE into fresh territory, but until that happens the current consolidation should be viewed as a test of whether the market has enough underlying demand to finally clear its most important resistance level.
UK100 Daily Candle Chart
Disclaimer:
All content is provided for general information only and should not be construed as any form of advice or personal recommendation. The provision of this content is not regulated by the Financial Conduct Authority.