


24th Jul 2026. 10.59am

Weekly Briefing – Friday 24th July
| Market | Movement this week (%)* |
|---|---|
| FTSE 100 | +0.75% |
| FTSE 250 | +0.48% |
| FTSE All-Share | +0.71% |
| AIM 100 | +1.44% |
| AIM All-Share | +1.22 |
* Price movement from Monday's open at 8am
Regency View:
Weekly Briefing – Friday 24th July
Market Overview
Dear Investor,
With earnings season in full swing and a new Prime Minister settling into Number 10, it would be easy to overlook geopolitics. Yet, as Brent crude pushes back towards $100 a barrel, the oil market is once again demanding investors’ attention.
For much of the conflict, each escalation has been met with the same conclusion: supply would continue to flow and prices would eventually settle back. This week’s rally suggests that confidence is beginning to fade.
The latest attacks on Saudi oil tankers in the Red Sea have prompted investors to reassess the risks surrounding global energy supplies. Brent has now rallied more than 35% since the start of July, breaking above key technical resistance and recovering much of the ground lost following May’s peak. Markets are no longer simply reacting to the headlines; they’re beginning to price the possibility that disruption could prove more persistent.
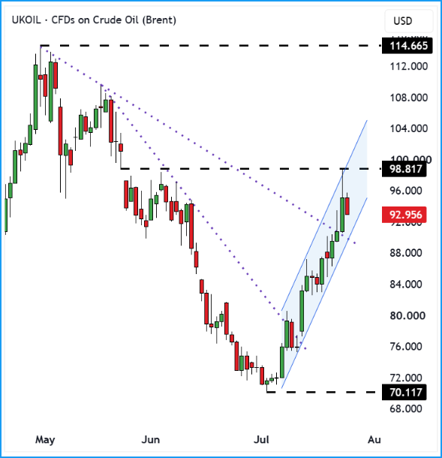
For investors, the implications stretch well beyond the energy sector. A sustained rise in oil prices would complicate the inflation outlook just as central banks were hoping price pressures were easing. As earnings season gathers pace, commentary around input costs and pricing power may become just as important as the headline profit figures.
Wishing you a great weekend,
Tom
Thomas Light – Chartered FCSI
Director of Research
Market Movers
On the rise: Renishaw (LSE: RSW) +11.8% on the week
Renishaw moved higher after revealing record fourth-quarter revenue and confirming full-year profits will comfortably exceed market expectations, capping off a year of steadily accelerating growth.
The precision engineering specialist expects full-year revenue of around £815 million, up 14% on the previous year, while adjusted profit before tax is forecast to rise 31% to approximately £167 million. Momentum gathered pace throughout the year, with fourth-quarter revenue climbing 27% year-on-year to a record £243 million as demand remained particularly strong across semiconductor manufacturing equipment and the aerospace and defence sectors.
Those end markets continue to provide powerful long-term tailwinds. Semiconductor manufacturers are investing heavily in next-generation production capacity, while defence and aerospace spending remains elevated across many developed economies. Renishaw’s highly specialised measurement and manufacturing technologies leave it well placed to benefit from both trends, helping explain why growth accelerated rather than slowed as the year progressed.
Regency View: Renishaw has long been regarded as one of the UK’s engineering success stories, but this update suggests growth is accelerating rather than simply continuing. The shares already command a premium valuation, yet record revenues and a 31% increase in profits show the business is continuing to earn it.
Marston’s shares slipped after investors focused on weaker underlying trading, overshadowing another confident update from the pub operator.
The group reported like-for-like sales down 1.6% for the year to date as quieter off-peak trading offset a strong summer boosted by the World Cup. England matchdays delivered a 22% increase in sales, while its recently introduced Grandstand pub format continued to outperform, generating around 30% like-for-like sales growth across converted sites.
Despite the softer headline sales figures, management reiterated full-year profit expectations and said its target for more than 200 basis points of EBITDA margin expansion would be achieved ahead of schedule. The company also expects leverage to fall sufficiently to allow shareholder returns, potentially through share buybacks, to resume next year. However, after a strong recovery in the shares over the past 12 months, investors appeared to focus on the slowdown in underlying trading rather than the improving operational backdrop.
Regency View: This felt more like a disappointment against heightened expectations than a deterioration in the investment case. Trading remains mixed, but improving margins, lower debt and the prospect of shareholder returns suggest the longer-term turnaround is still moving in the right direction.
Sector Snapshot
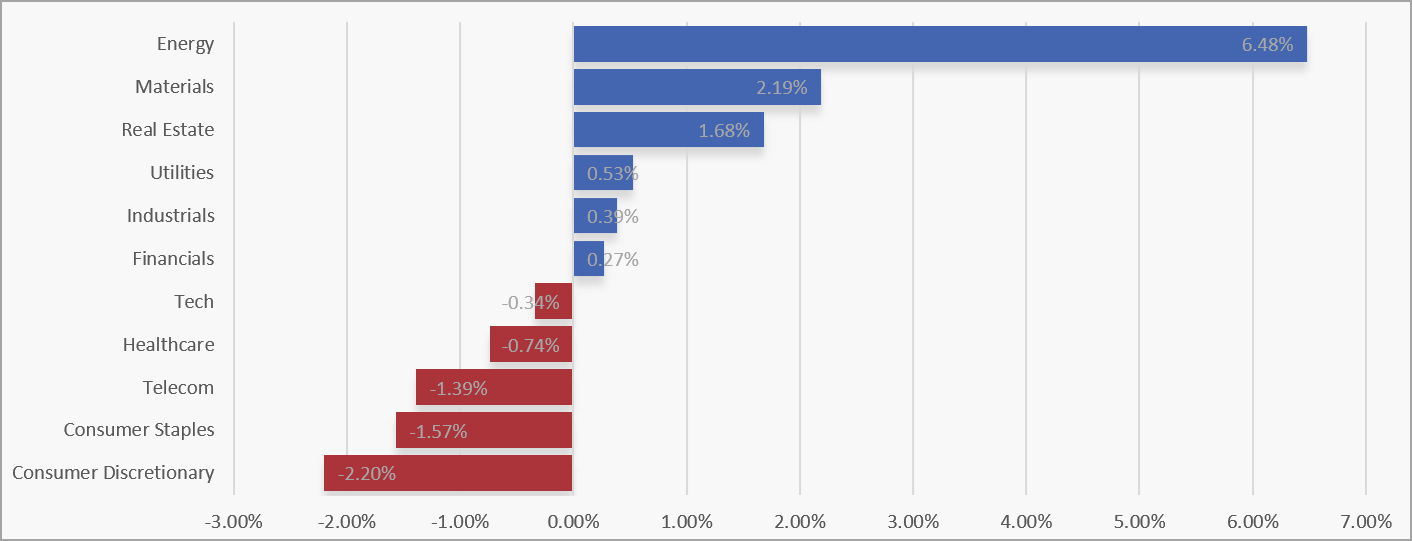
Energy led the UK market this week, extending its recent recovery as strength in oil prices continued to support the sector. Materials also performed well, while Real Estate maintained its improving momentum to finish among the week’s strongest performers.
At the other end of the leaderboard, Consumer Discretionary was the weakest sector as retailers and other consumer-facing businesses came under pressure. Consumer Staples also slipped despite recent resilience, while Telecoms and Healthcare both finished the week in negative territory.
UK Sector Performance (7-Days)
UK Price Action
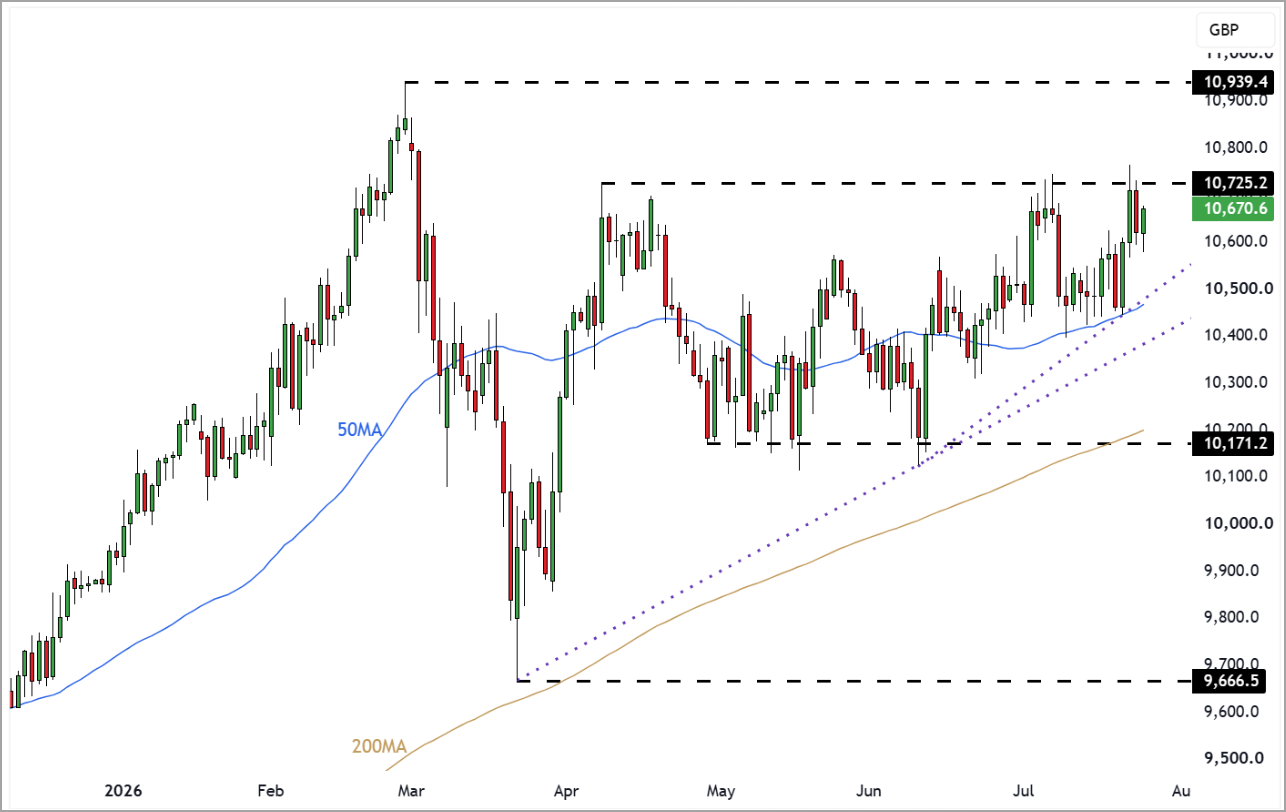
It’s been another quietly bullish week for the FTSE, although the market once again found resistance around the 10,700 level first established by the April swing highs. While the series of higher swing lows continues to suggest buyers are gradually gaining the upper hand, the market is yet to show it can sustain a move above resistance. Something will eventually have to give. A decisive break above 10,700 would leave the March highs firmly back in focus, while another rejection would suggest the FTSE still has more time to spend within this broad trading range.
UK100 Daily Candle Chart
Disclaimer:
All content is provided for general information only and should not be construed as any form of advice or personal recommendation. The provision of this content is not regulated by the Financial Conduct Authority.